.svg)
Edinburgh HMO Specialist
HMO Mortgages in Edinburgh
Edinburgh's HMO market operates under Scotland's distinct legal framework. Mandatory licensing from day one, Private Residential Tenancy law, and a premium rental market demand specialist broker expertise.
Edinburgh HMO Market Overview
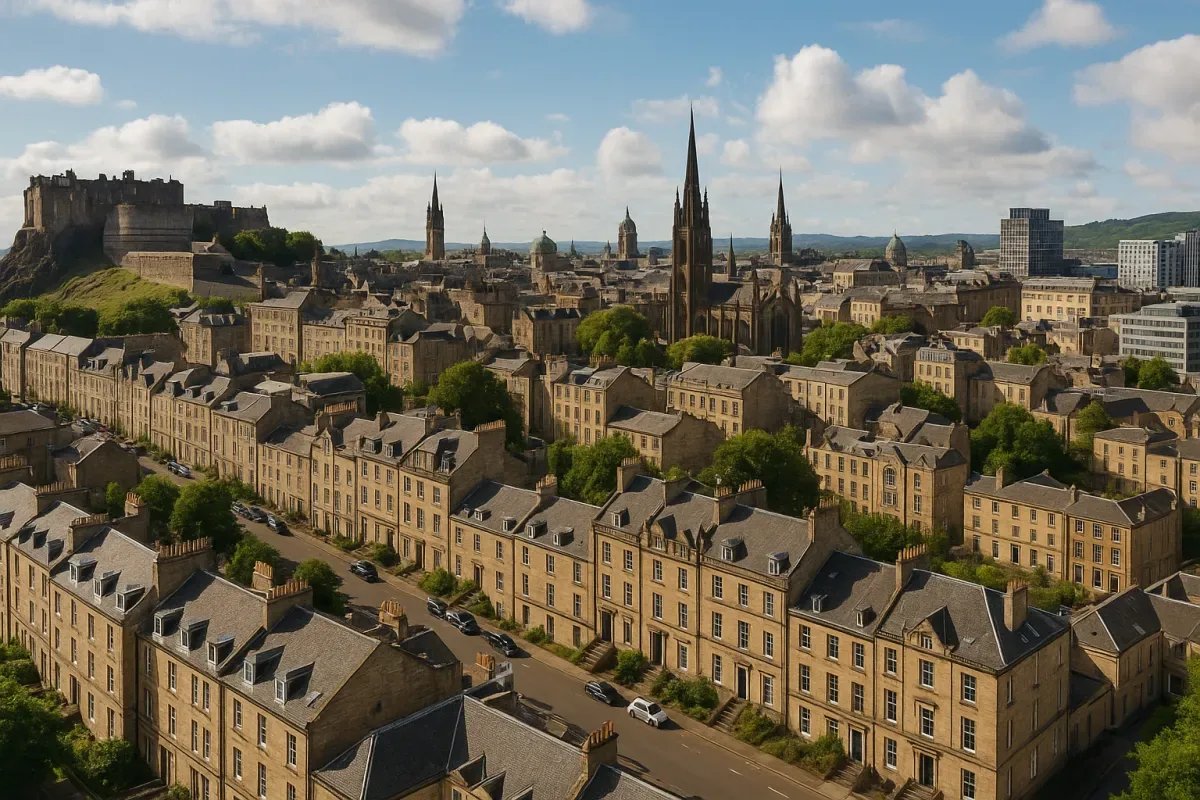
Edinburgh delivers HMO yields of 6–8% backed by exceptional and consistent rental demand. Scotland’s HMO framework is materially different from England — an HMO licence is required from day one for any property housing three or more unrelated people, and the Private Residential Tenancy (PRT) means Scottish tenancy law differs significantly from English law. Fewer lenders operate in Scotland, making specialist broker expertise essential.
Edinburgh is Scotland's capital city and one of the UK's most desirable rental markets. The city is home to four universities — the University of Edinburgh, Heriot-Watt University, Edinburgh Napier University, and Queen Margaret University — generating a combined student population of over 65,000. This creates strong, consistent demand for HMO accommodation across a well-established belt of student and young professional areas.
- Students across 4 universities
- 65,000+
- Typical gross HMO yields
- 6–8%
- Specialist HMO lenders we access
- 30+
Beyond students, Edinburgh's role as Scotland's financial capital — home to major employers including Standard Life Aberdeen, Baillie Gifford, and a thriving professional services sector — drives demand for quality co-living from young professionals. The city's tourism and hospitality sector, thriving tech community, and status as a UNESCO World Heritage Site all contribute to making Edinburgh one of the most in-demand rental markets in the UK.
Edinburgh HMO Licensing
Scotland's approach to HMO licensing is fundamentally different from England and Wales. Any landlord planning to let a property to three or more unrelated people in Scotland must hold a valid HMO licence before any tenants move in. There is no size or occupancy exemption.
Licensing rules are reviewed regularly at both national and council level — our guide to the current HMO licensing changes covers the latest requirements affecting landlords across the UK.
Article 4 Direction
HMO licence required for 3+ unrelated occupants — applies from the first day of occupation
Licence application submitted to Edinburgh City Council before tenants move in
Licences typically granted for three years (England's mandatory licences are for five years)
Detailed property standards must be met: room sizes, fire safety, amenity and management
Operating without a licence is a criminal offence in Scotland — not just a civil matter
The property must pass a fit and proper person test for all licence holders and managers
Top Edinburgh HMO Investment Areas
The table below provides a summary of the most popular areas for HMO investment in Edinburgh, with indicative gross yields and key characteristics.
| Area | Tenant Type | Typical Yield |
|---|---|---|
| Marchmont | Student/Professional | 6–7.5% |
| Newington | Student/Mixed | 6.5–8% |
| Morningside | Professional | 6–7% |
| Tollcross | Mixed | 7–8% |
| Leith | Professional/Mixed | 7–8% |
| Gorgie / Dalry | Mixed | 7–8.5% |
| Meadowbank / Portobello | Professional | 6.5–7.5% |
Yields are gross estimates based on typical room rents and purchase prices at the time of writing. Individual properties will vary. Always carry out your own due diligence.
Edinburgh HMO Mortgage Considerations
Fewer lenders for Scottish property
A subset of specialist HMO lenders operate in Scotland. Your broker must identify those comfortable with both Scottish HMO licensing and the Private Residential Tenancy framework.
Scottish conveyancing is different
Scottish property transactions use a solicitor-led process under Scots law. Your solicitor must be qualified in Scottish property law. English solicitors cannot act on Scottish property purchases.
Licence in place before completion
Many lenders will require the HMO licence to be in place before they release funds. Given Scotland's requirement for a licence before first occupation, this should be planned well in advance.
Strong demand supports valuations
Edinburgh's very low void rates, strong absolute room rents, and quality tenant base support robust investment valuations — a positive factor for lender appetite despite the Scottish-specific legal complexities.
Why Edinburgh for HMO Investment?
Persistent housing undersupply
Edinburgh has one of the most acute housing shortfalls of any UK city. High demand significantly exceeds supply, underpinning very low void rates and strong rental growth across the HMO market.
World-class universities
Four universities, led by the University of Edinburgh — consistently ranked in the global top 30 — generate over 65,000 students, creating sustained demand for quality HMO accommodation in Marchmont, Newington, and Tollcross.
Scotland's financial capital
Major financial employers including Standard Life Aberdeen, Baillie Gifford, and Lloyds Banking Group underpin demand for professional co-living from Edinburgh's large young professional population.
Strong capital growth history
Edinburgh property values have consistently outperformed the UK average over the long term. HMO investors benefit from reliable income and strong long-term capital appreciation.
Tourism-anchored economy
Edinburgh's status as a global tourist destination and home to the world's largest arts festival supports a year-round hospitality and creative economy that broadens the professional tenant base.
Frequently Asked Questions
Is Scotland's HMO licensing different from England?
Yes, significantly. In Scotland, HMO licensing is mandatory for any property rented to three or more unrelated people — there is no minimum occupancy threshold equivalent to England's five-person rule. The licence is required from day one of operation. Edinburgh City Council administers HMO licences in Edinburgh, and applications must be made before the property is occupied as an HMO. Licences are typically granted for three years and require compliance with detailed property standards.
How does Scotland's tenancy law affect Edinburgh HMO mortgages?
Scotland operates under the Private Residential Tenancy (PRT) framework, which replaced assured shorthold tenancies for new lets from December 2017. PRTs have no fixed end date — tenants have the right to remain indefinitely and landlords can only end the tenancy on one of eighteen specified grounds. This is an important difference from English tenancy law and affects how lenders assess risk. Specialist HMO lenders familiar with Scotland are essential for Edinburgh properties.
What yields can I achieve on an Edinburgh HMO?
Edinburgh HMOs typically achieve gross yields of 6–8%. Morningside, Marchmont, and Newington — established student and professional areas close to the University of Edinburgh — yield approximately 6–7.5%, while more affordable areas such as Leith and Tollcross can achieve 7–8%. Edinburgh's high property values compress percentage yields compared to northern English cities, but very strong and consistent rental demand and low voids underpin reliable income.
Can I get an HMO mortgage on an Edinburgh property?
Yes. A number of specialist HMO mortgage lenders actively lend on Edinburgh and Scottish properties. However, fewer lenders are set up for Scottish property than English, and lenders must be comfortable with Scotland's HMO licensing requirements and the Private Residential Tenancy framework. Using a specialist HMO mortgage broker with experience in Scottish property is strongly advisable to access the best available rates and avoid lenders who do not accept Scottish HMOs.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.