.svg)
LLP HMO Mortgages | Partnership Property Finance (2026)
Benefit from partnership flexibility with LLP HMO mortgages. Enjoy pass-through taxation and limited liability protection with market-leading rates from 4.8% and up to 75% LTV.
Limited Liability Partnership (LLP) HMO Mortgages at a glance
- Max LTV
- 75%
- Indicative rates from
- 4.8%
- Max term
- 25 years
- Typical timeline
- 6-8 weeks
Typically suits borrowers with
- Established LLP (2+ years trading)
- Filed LLP accounts required
- Designated members with property experience
Indicative figures; the rate and terms you're offered depend on your circumstances and the property.
What are Limited Liability Partnership (LLP) HMO Mortgages?
An LLP HMO mortgage is a loan taken out by a Limited Liability Partnership, rather than an individual or limited company, to buy or refinance an HMO. Profits are taxed at each member's personal rate rather than as corporation tax. Lenders usually want an LLP that has traded for two or more years, with filed accounts and experienced designated members.
An LLP combines the limited liability protection of a company with the operational flexibility of a partnership, making it an attractive structure for property investors working together.
Understanding LLP Structure for HMO Investment
Unlike limited companies, LLPs benefit from pass-through taxation where profits are taxed at individual partner rates rather than corporation tax rates.
This can be particularly advantageous for higher-rate taxpayers and provides more flexibility in profit distribution. Each partner receives their share of profits directly, which are then taxed at their personal tax rate rather than corporation tax rates.
The partnership structure allows for adaptable management arrangements, with designated members taking responsibility for day-to-day operations while all partners benefit from limited liability protection. This makes LLPs perfect for property investment partnerships where partners want to combine expertise and capital while maintaining operational flexibility.
LLP HMO Mortgage Requirements
LLP HMO mortgages require lenders who understand partnership structures and can assess multiple designated members' credentials and personal guarantees.
The partnership agreement must clearly define profit sharing, management responsibilities, and decision-making processes. Lenders will typically review the LLP's filed accounts, assess each designated member's experience and financial position, and require personal guarantees from key partners.
While application procedures may be more complex than individual mortgages, LLPs offer excellent opportunities for property investment partnerships with strong covenant strength and shared expertise. The combined experience and financial resources of multiple partners can often result in better lending terms and access to more market-leading rates.
If you're investing via a partnership, it's essential to understand how LLPs work for property investment.
Why use an LLP for HMO investment?
In short: LLPs combine pass-through taxation (profits taxed at partner level) with flexible profit sharing and limited liability for limited partners. They suit joint ventures between two or more investors who want clear partnership agreements and tax transparency without full corporation tax on retained profits.
Mortgage requirements for LLP borrowers
Most lenders want at least two years of LLP trading history, filed accounts, a formal partnership agreement, and personal guarantees from key partners. Rates are often similar to limited company HMO products, with LTV up to around 70–75% for strong cases. Adding or removing partners during the term usually needs lender consent. We structure LLP applications with the corporate documentation lenders expect from day one.
Other HMO Mortgage Types
Explore our other specialist solutions, or return to the hub for HMO mortgages.
Key Features of Limited Liability Partnership (LLP) HMO Mortgages
Partnership Flexibility
Benefit from adaptable partnership structure with shared management.
Pass-Through Taxation
Profits taxed at individual partner rates, not corporation tax.
Limited Liability
Protect personal assets through limited liability structure.
Shared Expertise
Combine partners' experience and investment capital.
Market-Leading Rates
Access specialist lenders offering market-leading LLP rates.
Professional Structure
Formal business structure for serious property investment.
Limited Liability Partnership (LLP) HMO Mortgages Eligibility Requirements
Understanding eligibility requirements helps you prepare a successful application. Our specialist lenders assess applications based on both property characteristics and borrower circumstances, with flexibility for experienced investors and first-time landlords alike. While these are general guidelines, many lenders offer flexible criteria. Our brokers work with specialist lenders who understand HMO investments and can find solutions even if you don't meet every requirement.
Property requirements
- Yes:Licensed HMO propertyThe property must have a valid HMO licence where required by local authority regulations. Lenders will verify licensing status before completion.
- Yes:Minimum 3 bedroomsMost lenders require a minimum of 3 bedrooms to classify as an HMO. Properties with more bedrooms typically qualify for higher loan amounts.
- Yes:Good rental locationProperties in areas with good transport links, local amenities, and strong rental demand typically receive more favourable lending terms.
- Yes:Strong rental demandLenders assess rental demand through local market analysis. Areas with high student populations or strong employment typically show stronger demand.
Borrower requirements
- Yes:Established LLP (2+ years trading)LLP HMO mortgages require an established Limited Liability Partnership, typically trading for 2+ years with filed accounts. This demonstrates the business structure is operational.
- Yes:Filed LLP accounts requiredLenders require evidence of filed LLP accounts to assess the business's financial position and trading history. Accounts should be up to date and filed with Companies House.
- Yes:Designated members with property experienceLLP designated members (partners) should have property investment experience. Lenders assess the experience and creditworthiness of all designated members.
- Yes:Clean credit history for guarantorsCredit history requirements vary by product type. Most lenders look for good credit, though some specialist products may be more flexible.
Common eligibility questions
What if I don't have landlord experience?
Many lenders accept first-time landlords, especially if you have a strong financial position, professional property management arrangements, or relevant business experience. Our brokers can help identify lenders suitable for your situation.
What credit score do I need for limited liability partnership (llp) hmo mortgages?
Most lenders look for good credit history, though some specialist lenders may consider cases with minor credit issues. Recent defaults or CCJs may limit your options, but we work with lenders who specialise in adverse credit cases.
Can I get a mortgage with less than 25% deposit?
While 25% deposit is standard, some lenders may offer up to 80% LTV (20% deposit) for experienced landlords with strong portfolios. Our brokers can assess your specific situation and identify lenders offering higher LTV options.
What if my property doesn't have an HMO licence yet?
Properties requiring an HMO licence must have valid licensing before mortgage completion. If you're purchasing a property that needs licensing, we can help coordinate the application process and work with lenders who understand HMO licensing requirements.
Limited Liability Partnership (LLP) HMO Mortgages Process
Our mortgage process, step by step.
- 1
LLP HMO Consultation
45 minutes - 2
LLP Application Process
2-3 days - 3
LLP Property Valuation
1-2 weeks - 4
LLP Underwriting
3-4 weeks - 5
LLP Legal Process
2-4 weeks - 6
LLP Completion
Same day
Limited Liability Partnership (LLP) HMO Mortgages Calculators
- LLP HMO Mortgage AffordabilityEstimate the loan an HMO's rent and value support when buying through an LLP
- Ltd vs LLP Tax ComparisonIllustrate tax for an HMO held personally, in an LLP or in a limited company
- LLP Property Tax CalculatorIllustrate income tax for LLP members on HMO profits, including Section 24
- LLP Profit Distribution CalculatorIllustrate tax for each member when LLP profits are split unequally
- HMO Mortgage CalculatorCalculate monthly payments and total costs for your HMO mortgage
- HMO Stamp Duty CalculatorCalculate stamp duty land tax including surcharges
Current Limited Liability Partnership (LLP) HMO Mortgages Rates
Live rates from our specialist lenders for limited liability partnership (llp) hmo mortgages. Monthly payments shown are calculated using a representative example of £250,000 loan amount.
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .
Limited Liability Partnership (LLP) HMO Mortgages Success Stories
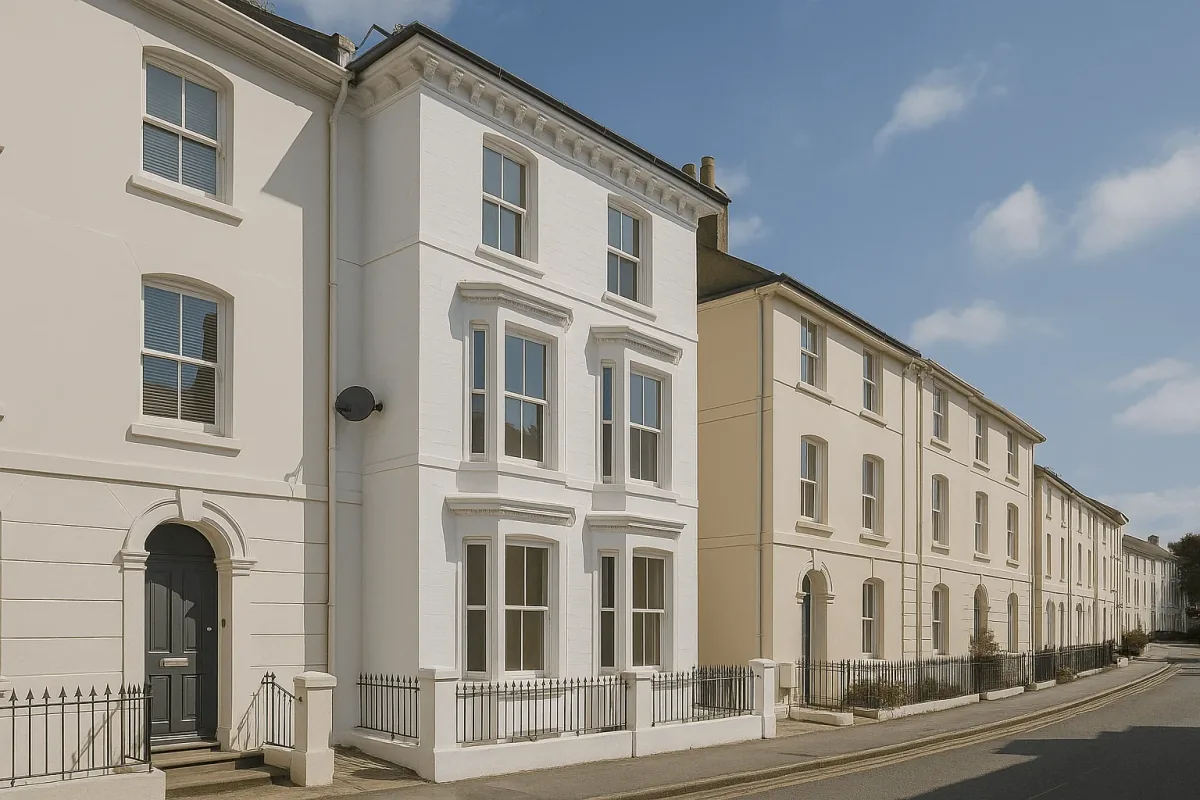
Bristol · £364K · 7 weeks
LLP Partnership Bristol HMO Expansion
Two experienced property investors formed an LLP to expand their HMO portfolio in Bristol, leveraging tax advantages and shared expertise.
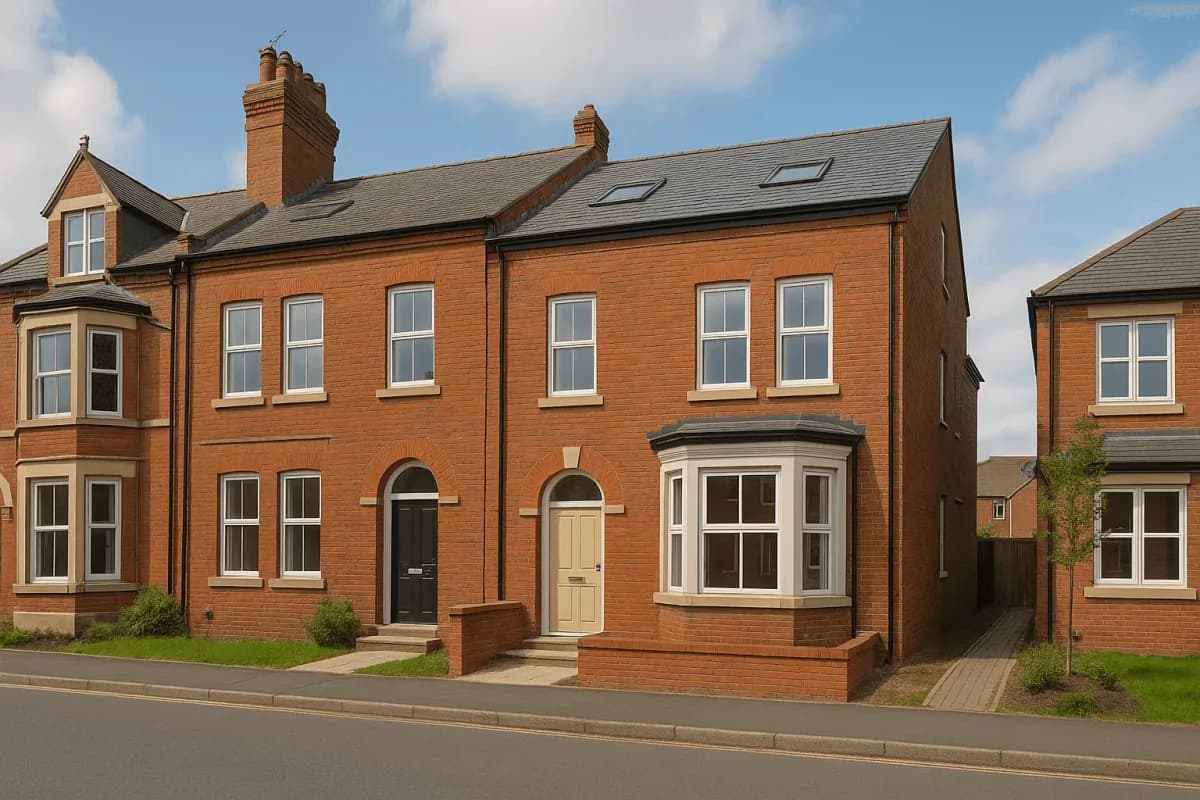
Manchester · £488K · 8 weeks
LLP Tax Efficiency: Manchester Portfolio Success
Established LLP structure for three partners to optimize tax efficiency across a growing Manchester HMO portfolio.
Limited Liability Partnership (LLP) HMO Mortgages Fees Guide
Typical costs involved with limited liability partnership (llp) hmo mortgages.
Arrangement Fee1% - 2.5%
- Paid to:
- Partnership Lender
- When:
- Completion
Fee charged by lenders specializing in LLP mortgages. Reflects additional complexity of partnership assessment.
Valuation Fee£400 - £1,000
- Paid to:
- HMO Surveyor
- When:
- Application
Professional HMO valuation including rental income assessment for LLP investment property.
Legal Fees£800 - £2,200
- Paid to:
- Partnership Solicitor
- When:
- Completion
Legal costs for LLP mortgage including partnership agreement review and multiple guarantee documentation.
Partnership Review£300 - £700
- Paid to:
- Legal/Accountancy Firm
- When:
- Application
Review of LLP structure, partnership agreement, and designated member arrangements.
Broker Fee0.75% - 1.5%
- Paid to:
- Partnership specialistBroker
- When:
- Completion
Fee for arranging LLP HMO mortgage. Specialist knowledge of partnership lending requirements.
Multiple Guarantor Setup£200 - £500
- Paid to:
- Legal Services
- When:
- Completion
Additional legal costs for setting up multiple personal guarantees from designated members.
Limited Liability Partnership (LLP) HMO Mortgages FAQs
What is an LLP HMO mortgage?
An LLP HMO mortgage is a specialised loan for Limited Liability Partnerships that own and operate Houses in Multiple Occupation. LLPs combine limited liability protection with operational flexibility, making them attractive for property investors working together.
David Sampson · Updated 10 May 2026
What are the tax advantages of using an LLP for HMO investment?
LLPs offer significant tax advantages for HMO investment. The key benefit is pass-through taxation - rental profits are taxed at individual partner rates (20%, 40%, or 45%) rather than corporation tax rates (19-25%). Partners can also claim mortgage interest relief against rental income without the Section 24 restrictions that affect individual landlords. Additionally, partners can offset losses against other income, and there's more flexibility in profit distribution between partners for tax efficiency.
Updated 17 May 2026
What are the differences between LLP and Limited Company HMO mortgages?
LLPs offer pass-through taxation (profits taxed at partner rates) while limited companies face corporation tax plus dividend tax. LLPs require all partners to be personally liable for guarantees, whereas limited companies can sometimes secure mortgages without director guarantees.
Updated 12 April 2026
Do all LLP partners need to provide personal guarantees for HMO mortgages?
Yes, most lenders require all LLP partners (or partners with significant ownership stakes, typically 20%+) to provide personal guarantees for HMO mortgages. This is because LLPs still require personal accountability for borrowed funds.
David Sampson · Updated 19 April 2026
What are the minimum requirements to set up an LLP for HMO investment?
To set up an LLP for HMO investment, you need: at least two partners, Companies House registration, a registered office address, an LLP agreement, and annual confirmation statements. Most lenders require 2+ years trading history.
Updated 26 April 2026
How do LLP mortgage rates compare to other HMO mortgage products?
LLP HMO mortgage rates are typically similar to limited company rates, usually 0.5-1.5% higher than personal mortgage rates. Rates typically range from 4.5-8% depending on the LLP's trading history, partner experience, property type, and loan-to-value ratio. Newly formed LLPs may face higher rates (6-8%) while established LLPs with strong financials can access more competitive rates (4.5-6%). The rate premium reflects the additional complexity and perceived risk of partnership structures compared to individual ownership.
Updated 17 May 2026
What documentation do lenders require for LLP HMO mortgage applications?
Lenders typically require: LLP incorporation certificate and agreement, 2-3 years of LLP accounts and tax returns, individual partner income evidence and credit checks, property valuation and rental assessments, and business plan for new acquisitions.
David Sampson · Updated 17 May 2026
Can LLPs use portfolio financing for multiple HMO properties?
Yes, LLPs are well-suited for portfolio financing across multiple HMO properties. Many specialist lenders offer portfolio products that allow LLPs to finance 3+ properties under a single facility, providing better rates and simplified administration.
Updated 17 May 2026
What happens to the mortgage if an LLP partner wants to leave?
When an LLP partner wants to leave, several options are available: 1) Buy-out by remaining partners using LLP funds or personal finance, 2) Bring in a new partner (subject to lender approval), 3) Refinance the mortgage excluding the departing partner, 4) Sell the property and distribute proceeds. Most lenders require notification and may reassess the mortgage based on remaining partners' financial strength. The LLP agreement should specify exit procedures, valuation methods, and buy-out terms to avoid complications.
Updated 8 March 2026
Are there any restrictions on LLP profit distribution for HMO investments?
LLPs have significant flexibility in profit distribution compared to limited companies. Partners can agree any profit-sharing arrangement in their LLP agreement - it doesn't need to match ownership percentages. However, lenders may impose restrictions: 1) Mortgage payments must be prioritized, 2) Minimum cash reserves may be required, 3) Large distributions might trigger covenant breaches. For tax efficiency, profits should be distributed in line with partners' tax positions, and timing can be managed to optimize annual allowances and tax bands.
Updated 17 May 2026
Limited Liability Partnership (LLP) HMO Mortgages Key Terms
- LLP (Limited Liability Partnership)A legal structure that combines the liability of a partnership with the tax benefits of a limited company, often used for property investment.
- LLP MortgageA mortgage product specifically designed for Limited Liability Partnerships, often with different terms and requirements than standard mortgages.
- LLP TaxationThe tax implications and obligations of a Limited Liability Partnership, including how profits are taxed and how partners are taxed on their share of profits.
- LLP Partnership AgreementThe legal document that outlines the terms and responsibilities of the partnership, including profit sharing, liability, and exit strategies.
CeMAP Qualified
DipFA
CeMAP (Certificate in Mortgage Advice and Practice)
DipFA (Diploma in Financial Advice)
15+ years mortgage industry experience
Arranged £187M+ in HMO lending
4,000+ clients helped
Founded The HMO Mortgage Broker
HMO Mortgages
Development Finance
Portfolio Lending
Commercial Finance
HMO Finance Specialist
Property Investment Specialist
About the author
David is the founder and senior HMO mortgage specialist with over 15 years of experience in property finance. He founded the firm in 2013, which has since helped 4,000+ landlords secure HMO finance.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.