.svg)
HMO Refurbishment Mortgages
HMO refurbishment mortgages: light versus heavy works, staged funding, exits onto a term HMO mortgage and how to apply.
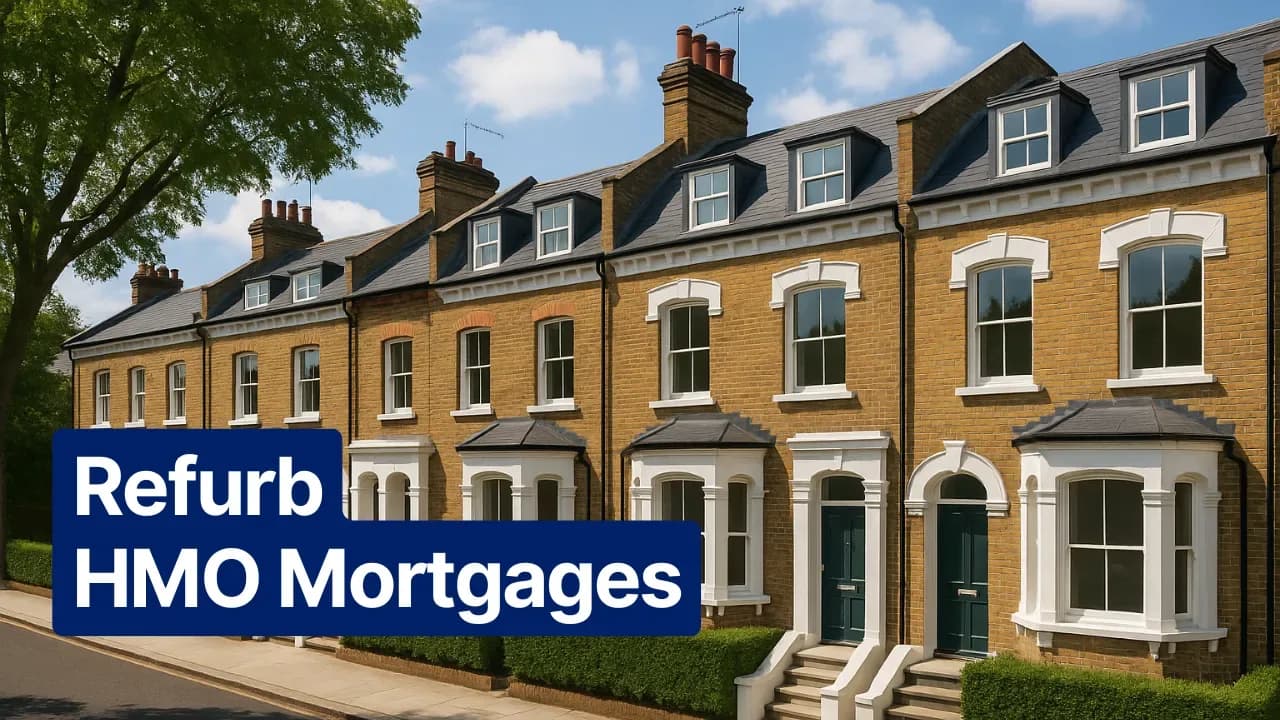
HMO Refurbishment Mortgages at a glance
- Typical timeline
- 6-8 weeks
Typically suits borrowers with
- Refurbishment experience preferred
- Strong project management skills
- Adequate financial resources
Indicative figures; the rate and terms you're offered depend on your circumstances and the property.
HMO refurbishment mortgages explained
An HMO refurbishment mortgage (or refurbishment finance) pays for a house you will improve or convert into a lettable HMO, then refinance onto a term HMO mortgages product. It sits between a ready-house term loan and full development finance. Light works can stay on a refurb-to-let facility. Heavy structural conversions usually need a bridge or a monitored development loan. Compare it with HMO bridging finance before you pick the wrapper.
There is no unsourced “from 6.2%” on this page. Cost is the facility rate plus fees and the months you hold it, then the term-mortgage rate on exit. Ask for a dated illustration. Anyone converting a house to an HMO should sequence planning, building control and the loan so the exit lender sees a licensable layout, not a shell.
Returns only count after finance. Gross yield on the finished rent versus purchase plus works plus finance months is the planning number. Net yield subtracts voids, bills, management and the licence. If that net figure only works at an 80% term LTV the exit panel will not offer, the refurb is not a finance problem — it is a project problem. Stress the rent the exit valuer will accept, not the brochure total.
Light vs heavy refurbishment
Lenders classify the works, not the estate agent. Light usually means cosmetic and compliance items that do not change the structure: fire doors, detection, kitchens, bathrooms, decoration, and a licence application on a house that already has the right number of rooms. Heavy means structural openings, new storeys, changing the use, or a full C3-to-HMO strip-out. The table is a decision aid, not a statute.
| Question | Light — often a refurb mortgage | Heavy — often a bridge or development loan |
|---|---|---|
| Structure | Walls and roof stay; rooms already exist | New openings, loft, rear extension, change of storeys |
| Planning | Use already lawful, or a simple C4 where permitted | Article 4, sui generis, or a change of use application |
| Time | Weeks to a few months | Many months with building control and a monitoring surveyor |
| Let during works | Sometimes, if safe and licensed | Usually empty |
| Exit | Term HMO mortgage on the same lender or a remortgage | Term mortgage only after GDV and licence are evidenced |
If you are unsure, describe the schedule of works in one page. The wrong label is how people take a light-refurb product and then cannot draw the next stage when the surveyor sees a knocked-through wall.
Refurbishment finance options
Refurb mortgage
A refurb-to-let or light-refurb HMO mortgage buys or remortgages the house and holds back or stages money for a defined schedule. Interest is often charged on the drawn amount. The exit is a term HMO product once works and the licence are done — sometimes a product switch with the same lender, sometimes a remortgage. This is the usual wrapper for fire-upgrades and amenity work on an already-C4 house.
Bridging + exit
A bridge is faster and more tolerant of an unlicensed or auction house. You pay a monthly rate for a short term, then refinance. Use it when 28-day completion or a heavy empty period makes a refurb mortgage too slow. It is not cheaper term debt.
Development finance
Monitored, staged against GDV, for conversions that look like a small development: new layouts, structural work, a planning condition. A monitoring surveyor signs each drawdown. First-time developers face tighter LTV and more cash in. Do not apply for development finance on a decoration job, and do not apply for a light-refurb mortgage on a three-storey rebuild. Some term HMO lenders will allow a small retention for leftover decoration on an otherwise lettable house. That is not refurbishment finance; it is a hold-back on a purchase. If the house cannot be licensed until the works finish, you need a works facility, not a retention.
Can you get a mortgage for renovation? Yes, on the right wrapper. A residential home-improvement loan is the wrong product for an HMO conversion. A standard buy-to-let will not fund an unlicensed strip-out. Choose refurb, bridge or development from the works, then the exit.
Staged funding and drawdowns
Staged funding means you do not get the works money on day one. The lender releases purchase funds, then further tranches when the surveyor confirms the last milestone. Typical gates are: strip-out complete, first-fix, fire package in, final fit-out, licence applied. Build the contractor’s cash-flow to those gates, not to your optimism. A builder who wants 80% upfront will break a staged facility.
Interest on undrawn money depends on the product. Some charge a commitment fee; some only charge on what is drawn. Model both. Keep a contingency in cash, not only on the spreadsheet — staged lenders will not always increase the facility when tiles cost more.
Exit: refinancing onto an HMO mortgage
Plan the exit on day one. The term lender will value the finished house, count lettable rooms that meet size and fire standards, and stress the rent. Timeline, in outline: works complete → building-control completion (if needed) → fire risk assessment → licence application or grant → tenancies or a realistic lettings plan → term valuation → refinance and repay the refurb facility.
Interest cover on the exit is the term lender’s test, not the refurb lender’s. This page does not invent a single ICR. The Mortgage Works publishes 175% ICR for all HMO applications (intermediary HMO criteria, checked 22 October 2026). Other exit lenders on our panel do not publish one HMO ICR on the pages cited. If the finished rent only works at an LTV the exit panel will not offer, the refurb loan has no exit.
Limited-company (SPV) refurbishment is common. The company still needs director guarantees and a schedule of works. A new SPV does not create development experience. Personal-name refurbishment can be simpler on a small light job if you already own your home and this HMO is an investment. Moving the finished house into a company later is a sale and a purchase for the lender and for stamp duty — budget the second set of fees before you treat it as a free tax move.
How many people can live in the house without it being an HMO? In England, three or more people who form more than one household and share a kitchen or bathroom usually make it an HMO. Two unrelated sharers are not normally an HMO. The refurbishment loan still needs the finished occupancy to match planning and the licence.
Costs and fees
Add arrangement or exit fees, valuation (sometimes two — current and GDV), monitoring surveyor visits, legal costs, and interest for every month until refinance. Then add the term-mortgage arrangement fee. A light refurb that overruns by three months can cost more in extra interest than a 0.3% difference in the headline rate. There is no live rate table here. Use a dated illustration and the calculators as a sketch.
Worked method — not a live offer. Add purchase or remortgage funds, the works budget, arrangement and legal fees, monitoring visits, and interest for the months until refinance. Subtract the term loan you can evidence on the finished valuation and stressed rent. The gap is cash you must keep. If that gap is larger than your reserve, cut the works or the price — do not assume the facility will grow.
Are HMO mortgages more expensive than single-let? Specialist products often price above vanilla buy-to-let because underwriting and valuation cost more. Refurbishment facilities sit higher still because they are short and staged. The saving is on the exit term rate once the house is licensed, not on the works loan. Current HMO rates for limited companies are not a single published figure on this page; a company refurb is priced on the facility, then the exit product.
MEES still applies when you let: in England a domestic private-rented house generally needs a valid EPC at the minimum band unless an exemption is registered. Fire and licence works that ignore insulation can leave you with a house you cannot legally let.
Criteria and documents
Put this in the pack before you apply:
- Schedule of works with quantities, not a paragraph of adjectives.
- Costings and contractor details; fixed-price where you can get it.
- Planning position (C4, sui generis, Article 4) and any permission.
- Building-control route if the works are notifiable.
- Licence path and a floor plan that matches the finished occupancy.
- GDV or finished-value evidence the valuer can use.
- Your experience, or a project manager if you have none.
- The exit: named term-product type and a realistic LTV.
First-time landlords should keep the first refurb light and the house small. A first 10-bed heavy conversion is a development case. Is it hard to get an HMO mortgage after refurbishing? It is routine when the licence, fire pack and rent roll match the drawings you sent at the start. It is hard when the finished house has fewer lettable rooms than the GDV assumed.
How soon can you refinance after refurbishing? As soon as the exit lender will value a licensable, readily lettable house. Some want rooms let; others will take a realistic lettings plan and a licence in progress. Empty newly finished stock can still pass if the valuer accepts the comparables. Do not promise a four-week refinance on a licence that the council says takes twelve.
Martin Lewis commentary on bridging is consumer-money advice, not an HMO refurbishment product. If a bridge is the right wrapper, price the months and the exit. If a refurbishment mortgage fits the works, use that instead of a more expensive monthly facility.
Get a refurbishment quote
Check how this affects your HMO mortgages enquiry. Send the schedule of works and say whether you think it is light or heavy, so we do not send a strip-out to a decoration product — or a fire-door package to a development desk.
When does refurbishment HMO finance make sense?
In short: when you are buying below market value and adding value through conversion or heavy modernisation before letting to HMO tenants. This includes family homes being split into rooms, tired HMOs needing compliance upgrades, or properties that will not meet licensing standards without works. Funds are usually released in stages after surveyor inspections at each milestone.
Exit strategy and typical terms
Most refurbishment loans run 6–18 months on interest-only terms, then refinance onto a long-term HMO mortgage once works complete and licensing is in place. Lenders need detailed costings, contractor quotes, and often a contingency buffer of 10–15%. Post-works valuation drives your exit LTV, so realistic build costs and timescales are essential. We help align bridging or refurbishment facilities with your long-term refinance lender to avoid costly delays at completion.
Related reading: HMO mortgages, converting a house to an HMO and HMO bridging finance.
HMO Refurbishment Mortgages Calculators
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .
HMO Refurbishment Mortgages FAQs
Can you get a mortgage for renovation?
Yes, on the right wrapper: a light HMO refurbishment mortgage, a bridge, or development finance. A residential home-improvement loan or a standard buy-to-let will not fund an unlicensed HMO strip-out.
David Sampson · Updated 22 October 2026
How many people can live in a house without it being a HMO?
In England a house is usually an HMO when three or more people who form more than one household share a kitchen, bathroom or toilet. Two unrelated sharers are not normally an HMO.
David Sampson · Updated 22 October 2026
What does Martin Lewis say about bridging loans?
That is consumer-money commentary, not an HMO product. If a bridge fits the works, price the months and the exit. If a refurbishment mortgage fits, use that instead.
David Sampson · Updated 22 October 2026
What are the current HMO mortgage rates for Ltd companies?
There is no single published Ltd-company refurbishment or exit rate on this page. A company facility is priced on the works loan, then the term product. Ask for a dated illustration.
David Sampson · Updated 22 October 2026
Are HMO mortgages more expensive?
Specialist HMO products often price above vanilla single-let. Refurbishment facilities sit higher still because they are short and staged. The saving is usually on the exit term rate once the house is licensed.
David Sampson · Updated 22 October 2026
Is it hard to get a HMO mortgage?
After a refurb it is routine when the licence, fire pack and rent roll match the drawings. It is hard when the finished house has fewer lettable rooms than the GDV assumed.
David Sampson · Updated 22 October 2026
Can I get a mortgage to refurbish an HMO?
Yes. Light compliance and amenity works often sit on a refurb-to-let facility. Heavy structural conversions usually need a bridge or development finance, then a term HMO mortgage.
David Sampson · Updated 22 October 2026
What is the difference between light and heavy refurbishment?
Light is cosmetic and compliance work that does not change the structure. Heavy is structural, a change of use, or a full strip-out. Lenders classify the works, not the estate agent.
David Sampson · Updated 22 October 2026
Do I need bridging finance for an HMO conversion?
If you must complete quickly or the house is unlicensed and empty for months, often yes. A slower light refurb on a lawful C4 house may not need a bridge.
David Sampson · Updated 22 October 2026
How soon can I refinance after refurbishing?
When the exit lender will value a licensable, readily lettable house. Some want rooms let; others take a lettings plan and a licence in progress. Do not promise four weeks on a twelve-week licence.
David Sampson · Updated 22 October 2026
What documents do lenders need for refurb finance?
A schedule of works, costings, planning position, building-control route if needed, licence path, floor plans, GDV evidence and your exit. First-time cases need more cash and a tighter project.
David Sampson · Updated 22 October 2026
What is an HMO mortgage?
An HMO mortgage is a specialist buy-to-let loan for a house in multiple occupation, where three or more people from more than one household share facilities. Lenders underwrite the combined room rents, licence position and valuation method rather than a single tenancy. Most high-street buy-to-let products do not cover this, so the case usually goes to a specialist lender.
David Sampson · Updated 21 October 2026
How much deposit do I need for an HMO mortgage?
Many specialist lenders offer up to 75% LTV on a small, licensed HMO, which means a deposit of around 25% of the valuation or purchase price. Larger HMOs, first-time landlords and pending-licence cases are often asked for more. The deposit is only one test: the rental stress test still has to pass on the room rents.
Milly Turner · Updated 21 October 2026
Can I get an HMO mortgage with no experience?
Some specialist lenders will consider a first HMO with no prior landlord experience if the deposit, location, licence plan and management arrangements are clear. Others want around 12 months of HMO or buy-to-let management. A professional managing agent and a property that already meets room-size and fire standards usually widens the panel.
Sarah Johnson · Updated 21 October 2026
CeMAP Qualified
CeMAP (Certificate in Mortgage Advice and Practice)
4+ years development finance experience
Arranged £25M+ in development finance
Development Finance Specialist
Development Finance
HMO Conversions
Commercial Finance
Refurbishment Loans
Development Finance Specialist
HMO Conversion Specialist
Commercial Property Advisor
About the author
Sarah specializes in HMO development finance and commercial property solutions.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .