.svg)
Specialist HMO finance since 2013
HMO mortgage broker for UK landlords
Compare 30+ specialist lenders for HMO mortgages, remortgages, bridging and development. Trusted by 4,000+ landlords since 2013.


- HMO clients helped
- 4,000+
- Largest loan arranged
- £9.5M
- Average time to DIP
- 4hr
- Average time to complete
- 28 days
Statistics Verification
Business Metrics: Internal company data (February 2026)
Lending Volumes: Lender panel application tracking
Client Numbers: Customer database and success tracking
Last Updated: February 2026
What we arrange
HMO Property Finance Types
Specialist finance for every stage of an HMO: buying, refinancing, refurbishing and building.
HMO Mortgages
Long-term mortgage products for Houses in Multiple Occupation.
HMO Remortgages
Options to refinance your existing HMO property or portfolio.
HMO Bridging Finance
Short-term financing for HMO purchases and renovations.
HMO Development Finance
Funding for new HMO developments or major conversions.
Lender panel
HMO Mortgage Lenders
We work with 30+ specialist lenders who understand HMO finance.
Why a specialist
Why Choose a Specialist HMO Broker?
How a dedicated HMO broker compares with a typical mortgage broker.
| Compared on | The HMO Mortgage BrokerDedicated HMO specialists | Typical mortgage brokerLimited HMO experience |
|---|---|---|
| Lender access | ||
| Lender access | Yes:Access to 30+ HMO lenders | No:Access to 3–5 HMO lenders |
| Yes:Priority access to HMO lenders | No:Slow access to HMO lenders | |
| Experience and knowledge | ||
| Experience and knowledge | Yes:10+ years of HMO lending experience | No:Variable HMO lending experience |
| Yes:Broad HMO property knowledge | No:Little or no HMO property knowledge | |
| Yes:Extensive HMO valuation experience | No:No HMO valuation experience | |
| Business focus | ||
| Business focus | Yes:97%+ of monthly business is HMO | No:Under 3% of monthly business is HMO |
| Yes:48–72 hour processing times | No:2–4 week processing times | |
Client results
Success Stories
Real results for our HMO clients.
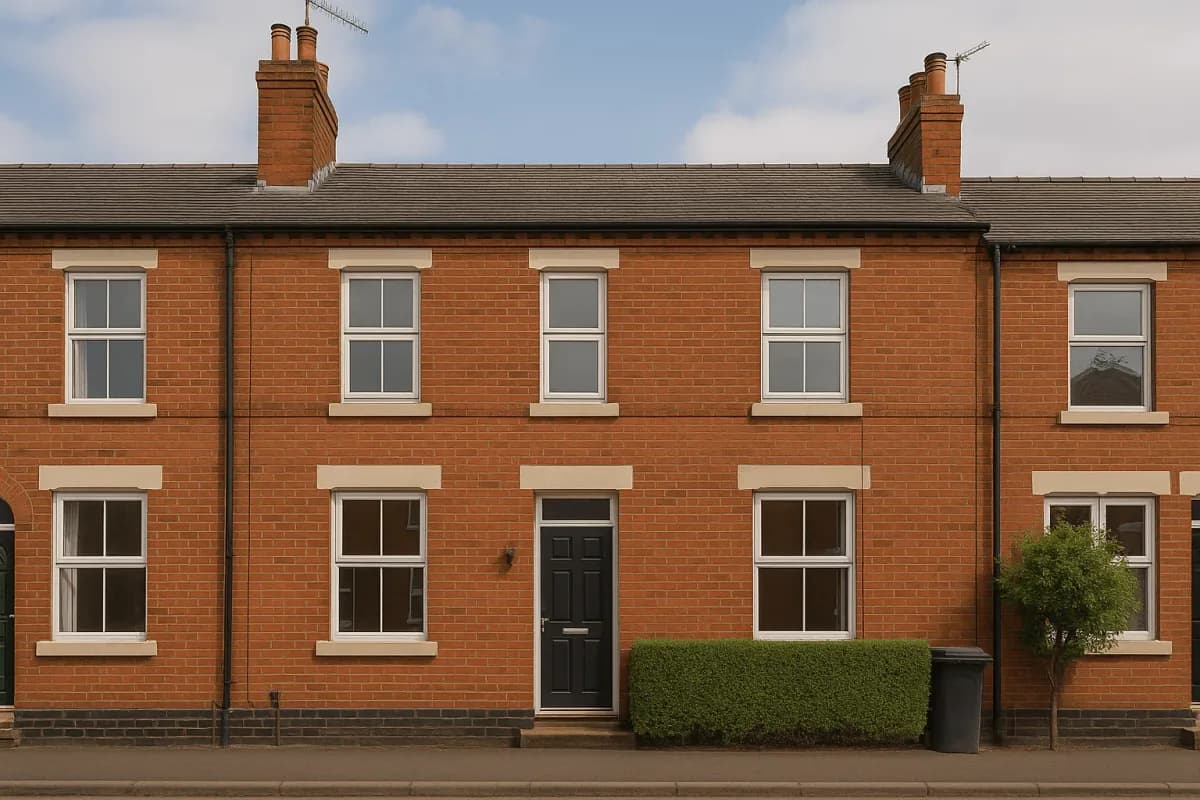
Manchester · £338K · 6 weeks
£450k Limited Company HMO in Manchester
Helped a property investor secure competitive financing for a 6-bedroom HMO through their limited company structure.
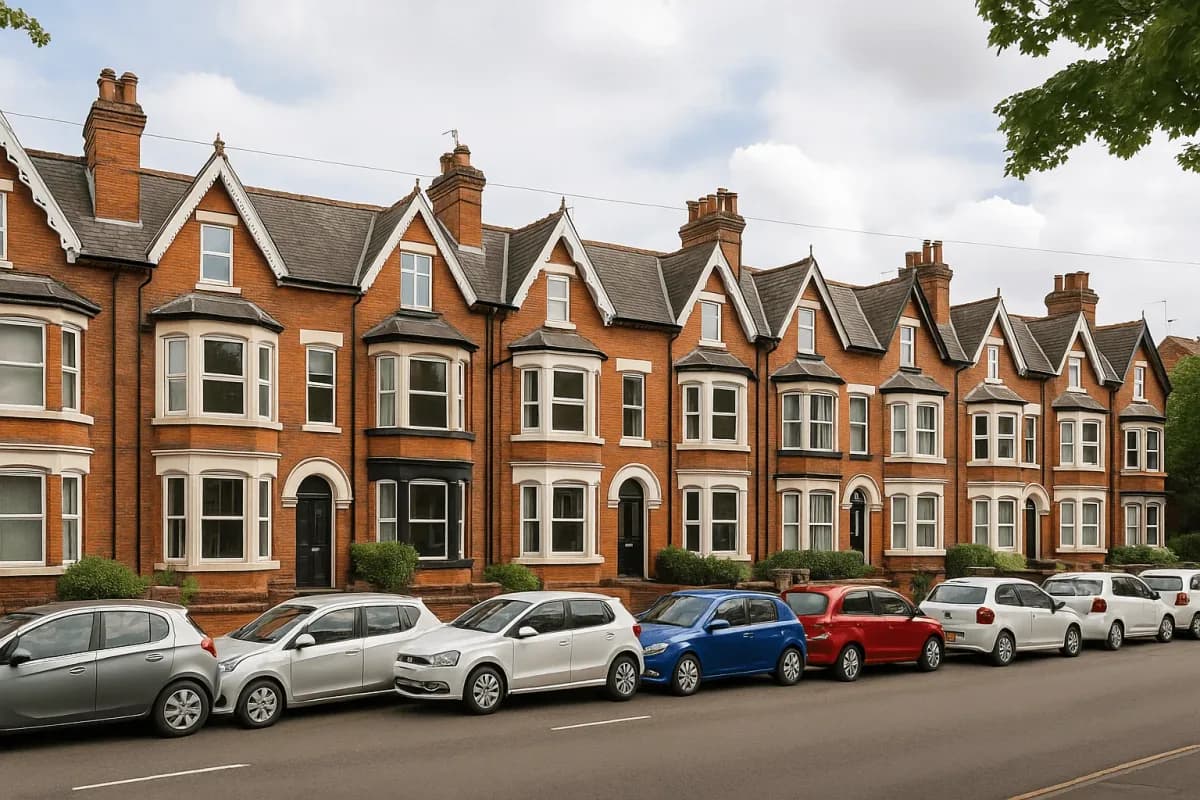
Birmingham (various) · £2.1M · 8 weeks
Portfolio Expansion: 10-Property HMO Portfolio
Secured portfolio financing for an experienced landlord expanding their HMO portfolio across Birmingham.
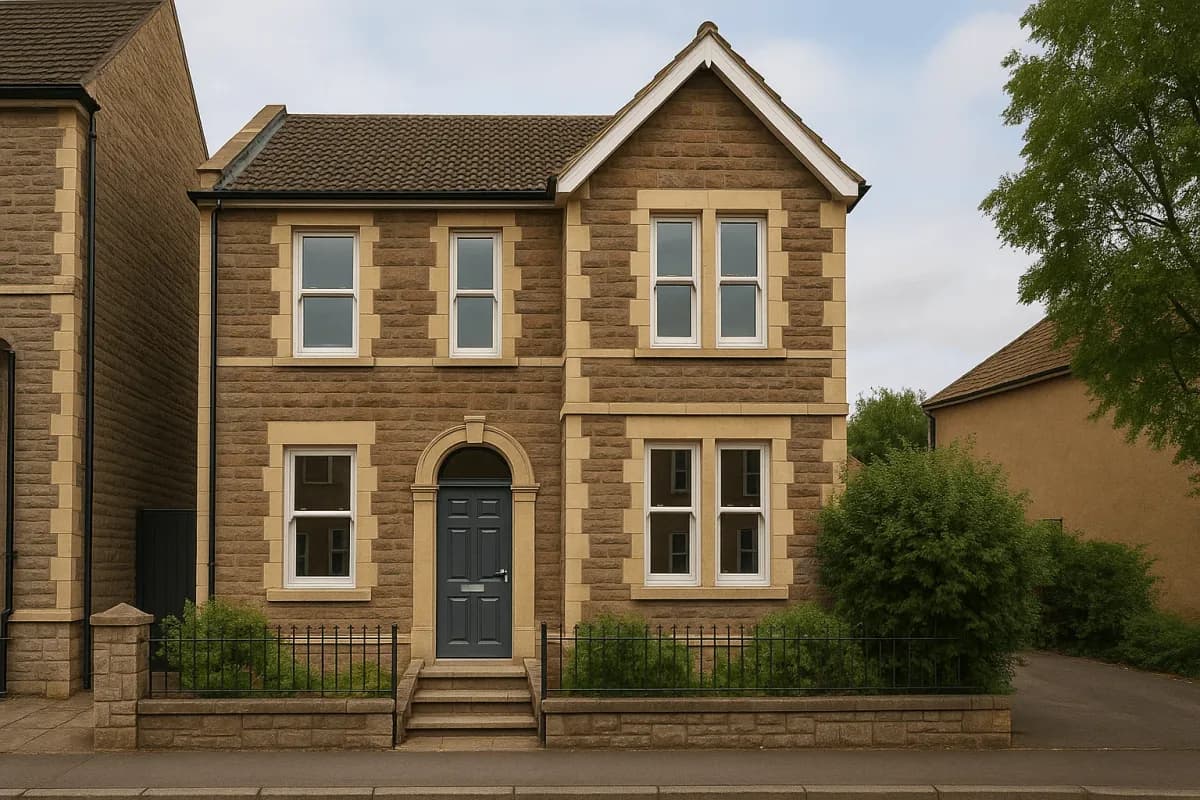
Bristol · £224K · 5 weeks
First-Time Landlord's HMO Success in Bristol
Guided a first-time landlord through their initial HMO purchase and helped secure favorable financing terms.
Rates
Indicative HMO Mortgage Rates
Typical specialist HMO rates at around 75% LTV. For the full comparison, see our rates page.
| Product | Term | Pay rate |
|---|---|---|
| Small HMOUp to 6 rooms | 2-year fix | 4.4–6.8% |
| Small HMOUp to 6 rooms | 5-year fix | 4.5–6.4% |
| Large HMO7+ rooms | 5-year fix | 4.6–7.2% |
| HMO trackerBank Rate 3.75% + margin | 2-year tracker | 4.0–6.9% |
Reviewed 15 Sept 2026. The effective rate includes the arrangement fee.
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .
Run the numbers
HMO Calculators
Work out borrowing, yields, costs and cashflow before you apply.
HMO Mortgage Calculator
Calculate monthly payments and total costs for your HMO mortgage
HMO Rental Yield Calculator
Calculate potential returns with gross and net yields
HMO Stamp Duty Calculator
Calculate stamp duty land tax including surcharges
HMO Cashflow Calculator
Project monthly and annual cashflow for your property
HMO Remortgage Calculator
See potential savings by refinancing your HMO mortgage
HMO Bridging Calculator
Calculate short-term financing and bridging loan costs
FAQs
Frequently Asked Questions
Answers to common questions about HMO mortgages.
What is an HMO mortgage?
An HMO (House in Multiple Occupation) mortgage is a specialist buy-to-let mortgage designed for properties rented out by at least three tenants who are not from the same household but share facilities like the kitchen or bathroom. These mortgages cater to the unique risks and higher rental income potential of HMO properties.
David Sampson · Updated 10 March 2026
How do HMO mortgage lenders assess affordability?
HMO mortgage lenders typically assess affordability based on the property's rental income, often using a stress test. They consider individual room rents rather than the overall property rent and apply a higher interest cover ratio (ICR) because of the increased perceived risk.
Sarah Johnson · Updated 10 March 2026
What are the criteria for an HMO property?
An HMO property is generally defined as a property rented out by at least three people who are not from one household but share toilet, bathroom or kitchen facilities. Larger HMOs (5+ tenants) usually require a mandatory licence, with additional licensing imposed by some councils for smaller HMOs.
Milly Turner · Updated 10 March 2026
Can I get an HMO mortgage with bad credit?
Yes. Specialist HMO lenders will consider applicants with adverse credit histories provided there are mitigating circumstances and a strong overall application. Expect to provide a larger deposit or pay a higher rate.
David Sampson · Updated 10 March 2026
What deposit is required for an HMO mortgage?
Deposits typically range from 25% to 35% of the property value—higher than standard buy-to-let products due to the specialist nature and risk profile of HMOs.
Sarah Johnson · Updated 10 March 2026
Are HMO mortgages more expensive?
Rates and arrangement fees can be slightly higher than standard buy-to-let mortgages because HMO lending is more complex. The stronger rental yields from HMOs often offset the additional cost.
Milly Turner · Updated 10 March 2026
What is an HMO licence?
An HMO licence is a legal requirement for certain multi-let properties. It ensures the property meets specific amenity and safety standards and that the landlord is fit and proper. Mandatory licensing applies to large HMOs (5+ tenants), with some councils requiring licences for smaller ones.
David Sampson · Updated 10 March 2026
How long does an HMO mortgage application take?
Most HMO applications take 4–12 weeks depending on valuation, legal work, and lender processing times. Working with a specialist broker can help compress timelines.
Sarah Johnson · Updated 10 March 2026
Can I convert a property into an HMO?
Yes. Many investors purchase properties to convert into HMOs using refurbishment finance or bridging loans, then refinance onto an HMO mortgage once works complete. Always verify planning permission and building regulations first.
Milly Turner · Updated 10 March 2026
What are the benefits of an HMO property?
HMOs typically deliver higher rental yields and diversified income because rent is collected per room. They suit landlords willing to manage compliance, licensing, and multiple tenants.
David Sampson · Updated 10 March 2026
Insights
Latest Blog Posts
Guides and market updates for HMO landlords.