.svg)
Birmingham HMO Specialist
HMO Mortgages in Birmingham
Birmingham is one of the UK's most compelling HMO markets. Three universities, a large young professional population, and yields of 7–10% make it a standout location for HMO investment.
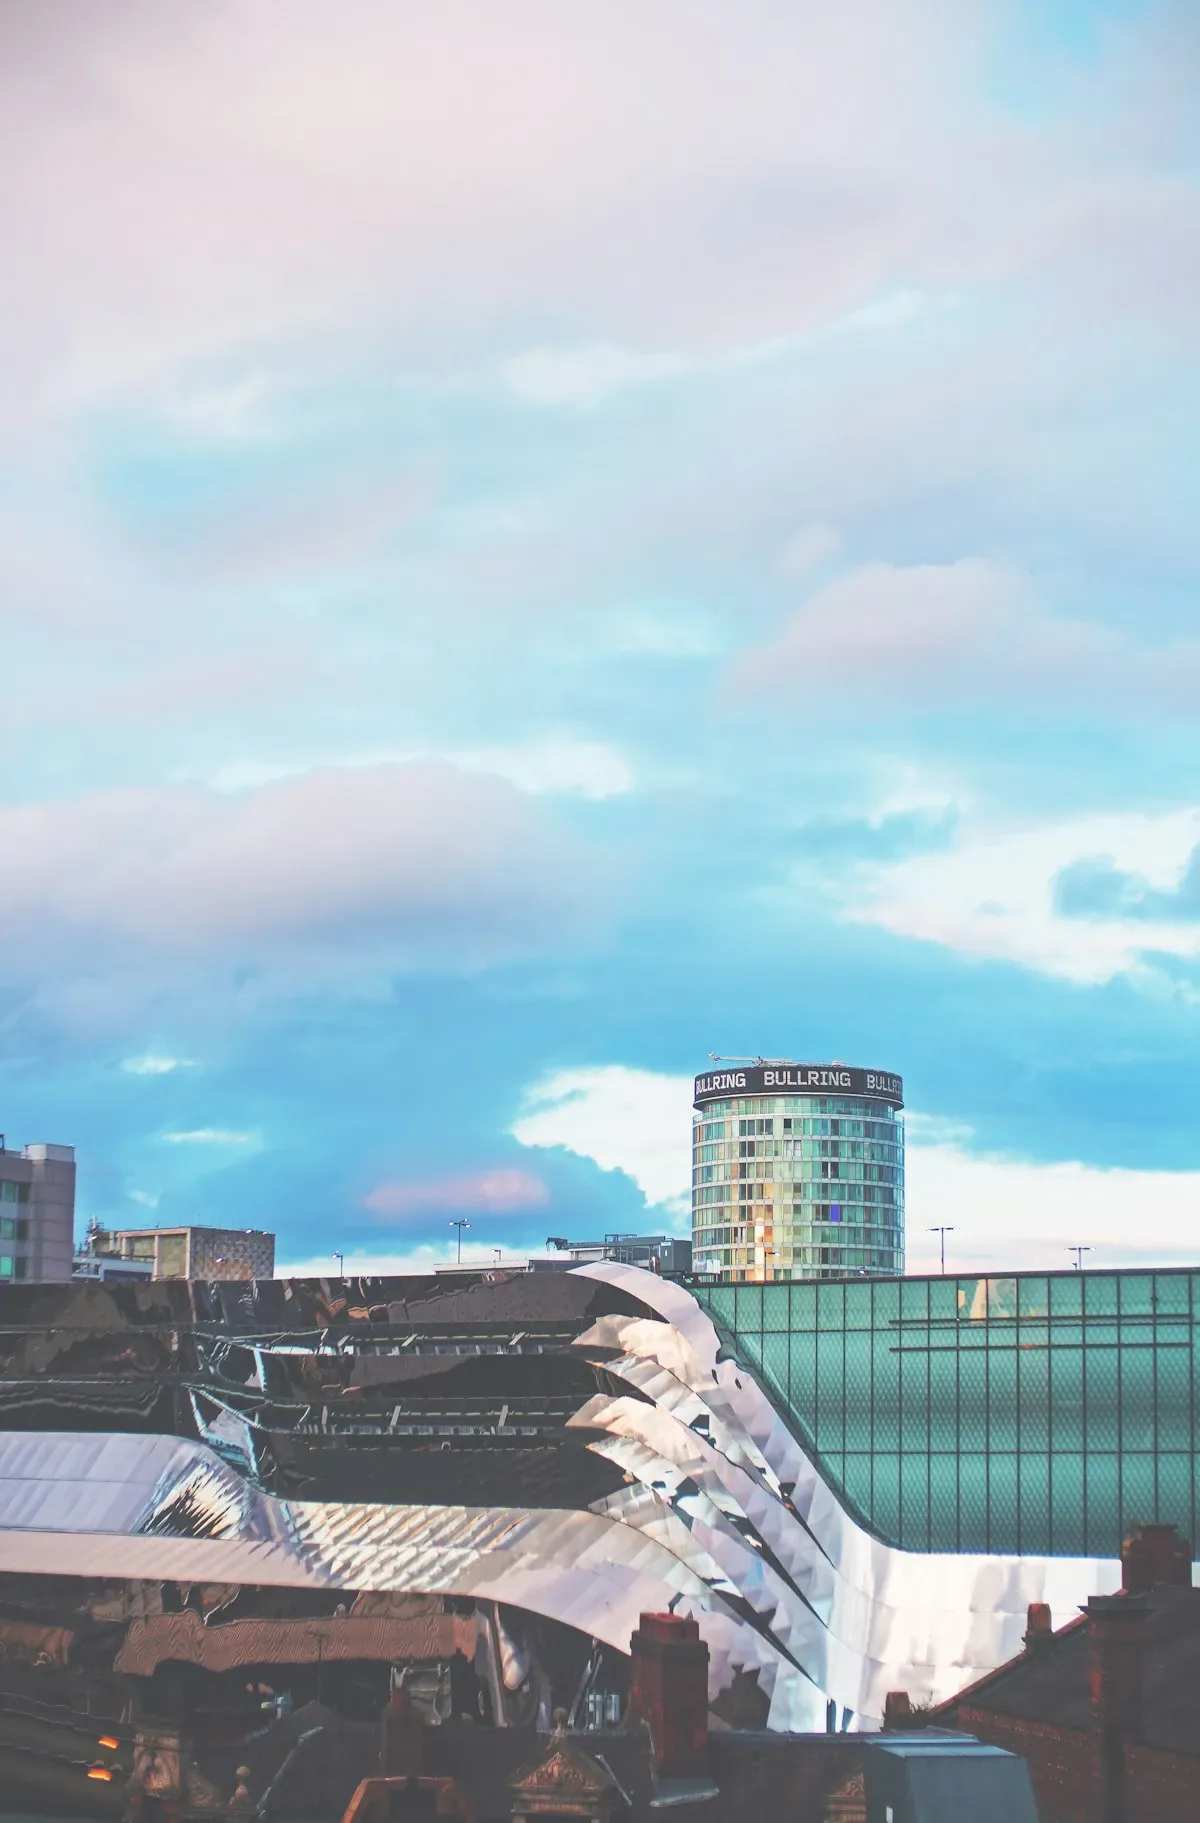
Birmingham HMO Market Overview
Birmingham consistently delivers HMO yields of 7–10% — well above the national average. Three major universities generate tens of thousands of students each year, while the city’s rapidly growing professional population underpins strong demand across a wide range of areas. Article 4 Directions are in force in Selly Oak and Edgbaston — understanding the planning and licensing position is essential before purchasing.
Birmingham is the UK's second-largest city and one of the most dynamic HMO investment markets outside London. The city benefits from three major universities — the University of Birmingham, Aston University, and Birmingham City University — generating over 70,000 students and creating consistent demand for quality shared housing across a broad range of locations and price points.
- Students across 3 universities
- 70,000+
- Typical gross HMO yields
- 7–10%
- Specialist HMO lenders we access
- 30+
Beyond the student market, Birmingham's rapid economic growth — driven by financial services, tech, and major regeneration projects including the transformation of Digbeth and the wider City Centre — has created a large and growing young professional population that actively seeks HMO-style co-living as a cost-effective and flexible housing option.
The combination of relatively affordable property prices, strong room rents relative to purchase cost, and consistently low void rates in well-established student areas makes Birmingham one of the most compelling HMO investment cities in England.
Birmingham HMO Licensing
Birmingham's HMO licensing framework combines mandatory national requirements with locally imposed additional licensing schemes across many of the city's wards. Understanding which rules apply to your specific property and area is critical before purchasing.
Licensing rules are reviewed regularly at both national and council level — our guide to the current HMO licensing changes covers the latest requirements affecting landlords across the UK.
Article 4 Direction
Beyond mandatory licensing, Birmingham City Council operates additional licensing schemes across a number of wards, extending licensing requirements to smaller HMOs with fewer than five occupants. The scope of these schemes changes over time, so always verify the current position with the council directly. Many lenders will require sight of a valid licence, or confirmation that the property does not require one, before completing on an HMO mortgage.
Top Birmingham HMO Investment Areas
The table below provides a summary of the most popular areas for HMO investment in Birmingham, with indicative gross yields and key characteristics.
| Area | Tenant Type | Typical Yield |
|---|---|---|
| Selly Oak | Student | 8–10% |
| Edgbaston | Mixed | 7–9% |
| Moseley | Professional | 7–9% |
| Erdington | Mixed | 8–10% |
| Bournville | Professional | 7–8.5% |
| City Centre / Digbeth | Professional | 7–9% |
| Aston / Lozells | Mixed | 8–10% |
Yields are gross estimates based on typical room rents and purchase prices at the time of writing. Individual properties will vary. Always carry out your own due diligence.
Birmingham HMO Mortgage Considerations
Wide lender choice
Birmingham's lower property values mean fewer lenders hit maximum loan size caps. More specialist HMO lenders are comfortable with the Birmingham market.
Strong rental coverage
Birmingham's 7–10% yields mean rental income typically comfortably covers stress-tested mortgage payments, improving your chances with more conservative lenders.
Accessible deposit requirements
25–30% is typically sufficient for a Birmingham HMO mortgage. On a £200,000 property that means £50,000–£60,000 — far more accessible than London equivalents.
Specialist lenders still required
Despite being more accessible, Birmingham HMOs still require specialist HMO mortgage lenders. Standard buy-to-let lenders will not accept HMO properties.
Why Birmingham for HMO Investment?
Young population
Birmingham has the youngest city-centre population of any major UK city. This creates deep, sustained demand for shared housing across the full range of price points and locations.
Regeneration pipeline
Major regeneration projects including the transformation of Digbeth into a creative and tech quarter, and the wider City Centre masterplan, are creating new professional residential demand adjacent to established HMO zones.
Strong student base
Three universities with over 70,000 students create resilient, year-round HMO demand in Selly Oak, Edgbaston, and Aston. Student HMO demand is remarkably consistent and resistant to economic cycles.
Infrastructure investment
HS2 and the wider connectivity improvements are strengthening Birmingham's economic fundamentals and attracting new businesses and workers, increasing long-term demand for quality rental accommodation.
Established HMO infrastructure
Birmingham has a well-developed ecosystem of HMO management agents, specialist solicitors, and experienced surveyors, making it easier to build and operate a portfolio efficiently.
Frequently Asked Questions
What yields can I achieve on a Birmingham HMO?
Birmingham HMOs typically achieve gross yields of 7–10%, making it one of the strongest HMO markets in the Midlands. Student areas such as Selly Oak and Edgbaston regularly produce yields of 8–10%, while professional areas like Moseley and Erdington tend to yield 7–9%. The combination of lower purchase prices relative to the South and strong room rents makes Birmingham very attractive for HMO investors.
Does Article 4 apply to Birmingham HMOs?
Yes. Birmingham City Council has Article 4 Directions in force in Selly Oak and Edgbaston — the primary student HMO areas close to the University of Birmingham. This means converting a standard dwelling house (Use Class C3) to a small HMO (Use Class C4) in these areas requires planning permission. Purchasing an existing, licensed HMO in an Article 4 area is generally straightforward for mortgage purposes, provided you have evidence of lawful HMO use.
Do I need an HMO licence in Birmingham?
Yes. Mandatory HMO licensing applies to all properties in Birmingham with five or more occupants from two or more households sharing facilities. Birmingham City Council also operates additional licensing schemes in many wards, extending requirements to smaller HMOs. Always verify the exact licensing position with the council before exchanging contracts, as operating without a licence can result in civil penalties of up to £40,000 and a rent repayment order.
Can I get a Birmingham HMO mortgage as a first-time landlord?
Yes. Birmingham's strong student and professional rental market, combined with more accessible property prices than London, means that a number of specialist HMO lenders are willing to consider first-time landlords. You will typically need a 25–30% deposit and a solid personal income profile. A specialist HMO mortgage broker can identify the lenders most open to less experienced investors in the Birmingham market.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.