.svg)
Bristol HMO Specialist
HMO Mortgages in Bristol
Bristol is one of England's most sought-after HMO markets. Exceptional tenant demand, very low void rates, and citywide selective licensing make specialist mortgage advice essential.
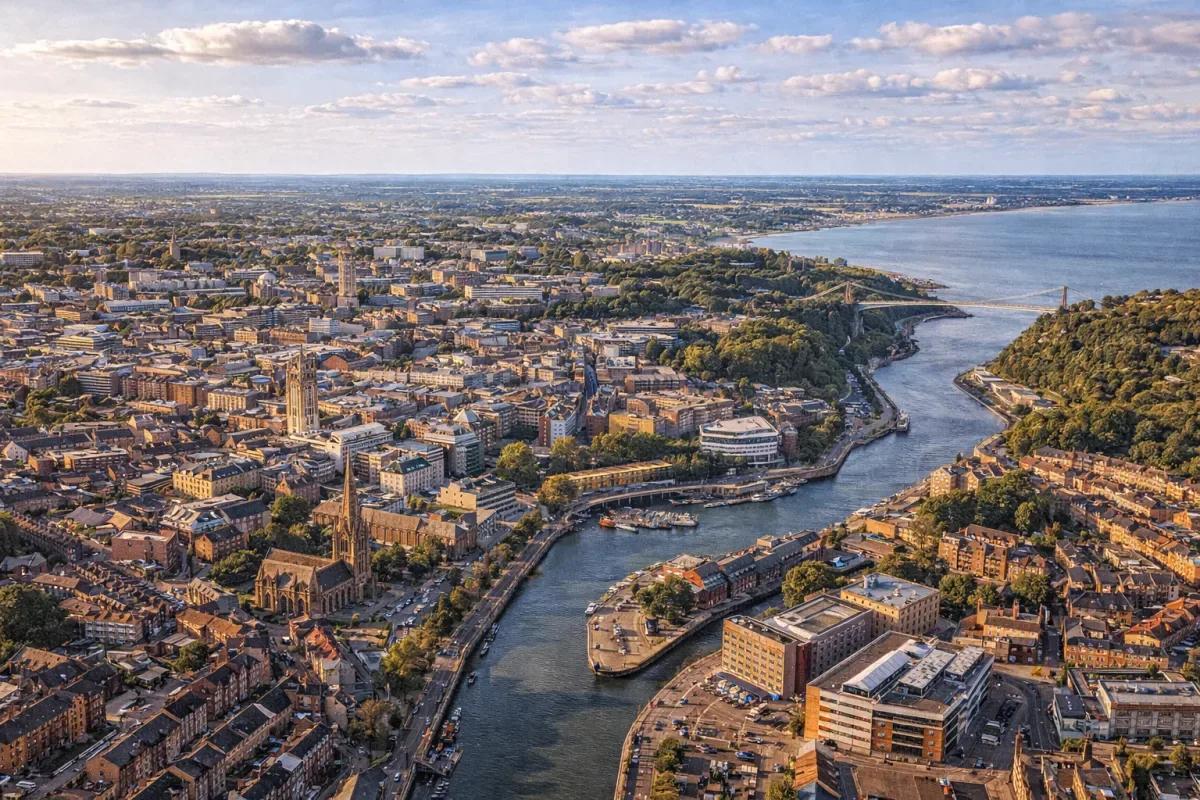
Bristol HMO Market Overview
Bristol delivers HMO yields of 6–9% — lower than northern cities in percentage terms but backed by some of the strongest and most resilient rental demand in England. The city operates one of the most extensive selective licensing schemes in the country, covering large areas of Bristol. Article 4 Directions are in force in Clifton and Redland. Understanding the compliance landscape is essential for investors and lenders alike.
Bristol is consistently ranked as one of the UK's most desirable places to live, work, and study. The city is home to two major universities — the University of Bristol and the University of the West of England (UWE) — generating over 50,000 students and creating sustained demand for quality HMO accommodation across a range of established student areas.
- Students across 2 major universities
- 50,000+
- Typical gross HMO yields
- 6–9%
- Specialist HMO lenders we access
- 30+
Beyond the student market, Bristol has established itself as a major tech, aerospace, media, and creative hub. Companies including Airbus, Rolls-Royce, the BBC, and a thriving cluster of tech start-ups and scale-ups employ tens of thousands of professionals, many of whom prefer HMO-style co-living as an affordable and flexible housing option in a city where house prices have risen significantly.
Bristol HMO Licensing
Bristol City Council operates one of the most comprehensive private rental licensing frameworks of any English city. The combination of mandatory HMO licensing, additional licensing, and extensive selective licensing means that most private rented properties in Bristol require some form of council licence.
Licensing rules are reviewed regularly at both national and council level — our guide to the current HMO licensing changes covers the latest requirements affecting landlords across the UK.
Article 4 Direction
Article 4 Directions in force in Clifton and Redland — planning permission required for new conversions
Selective licensing covers large parts of Bristol — verify requirements for your specific property
Mandatory HMO licensing for all properties with 5+ occupants from 2+ households
Operating without required licences: civil penalties up to £40,000 and rent repayment orders
Many lenders require evidence of valid licences before completing an HMO mortgage in Bristol
Top Bristol HMO Investment Areas
The table below provides a summary of the most popular areas for HMO investment in Bristol, with indicative gross yields and key characteristics.
| Area | Tenant Type | Typical Yield |
|---|---|---|
| Clifton | Student/Professional | 6–8% |
| Redland | Student/Professional | 6.5–8.5% |
| Bedminster | Mixed | 7–9% |
| Easton | Mixed | 7–9% |
| Fishponds | Student/Mixed | 7–9% |
| Stokes Croft / St Pauls | Professional | 7–8.5% |
| Southville | Professional | 6.5–8% |
Yields are gross estimates based on typical room rents and purchase prices at the time of writing. Individual properties will vary. Always carry out your own due diligence.
Bristol HMO Mortgage Considerations
Higher property values
Bristol prices are significantly higher than northern cities. Some lenders' maximum loan size caps can become relevant, particularly in Clifton and Redland. Specialist lenders can accommodate larger loan sizes.
Licensing compliance critical
Given Bristol's extensive selective and additional licensing, lenders will pay close attention to the property's licensing position. Having all required licences in place before applying for a mortgage is strongly advisable.
Strong demand supports valuations
Bristol's extremely low void rates and high absolute room rents support strong investment valuations. RICS surveyors familiar with the Bristol HMO market will assess the property on an investment basis.
Quality tenant base
Bristol's tenant base — a mix of university students, young tech and creative professionals, and key workers — is attractive to lenders as it points to lower risk of rental arrears and voids.
Why Bristol for HMO Investment?
Persistent housing undersupply
Bristol has one of the most severe housing shortfalls of any English city. The gap between housing supply and demand directly underpins very low void rates and strong rental growth across the HMO market.
Exceptional quality of life
Bristol consistently ranks as one of the UK's most desirable places to live. This draws professionals from across the UK and internationally, sustaining deep and diverse HMO demand year-round.
Tech and creative economy
A thriving tech, aerospace, and creative sector anchored by Airbus, Rolls-Royce, the BBC, and a large cluster of digital businesses creates sustained professional co-living demand across the city.
Strong capital growth history
Bristol property values have consistently outperformed the national average over the long term. HMO investors benefit from both strong income returns and capital appreciation in most areas.
Two major universities
The University of Bristol and UWE together generate over 50,000 students, creating resilient year-round demand for quality student HMOs in Clifton, Redland, and Fishponds.
Frequently Asked Questions
What yields can I achieve on a Bristol HMO?
Bristol HMOs typically achieve gross yields of 6–9%. Student and young professional areas such as Redland, Clifton, and Bedminster produce yields in the 6.5–8.5% range, while more affordable areas such as Easton and Fishponds can achieve 7–9%. Bristol's property prices are higher than northern cities but the city's exceptionally low void rates and very strong rental demand support consistent income and strong long-term capital appreciation.
Does selective licensing apply to all Bristol HMOs?
Bristol City Council operates one of the most extensive selective licensing schemes in England, covering large parts of the city. This means that many private rented properties in Bristol — not just larger HMOs — require a licence. Always verify whether your specific property falls within a selective licensing zone before purchasing, as operating without the required licence can result in substantial fines and rent repayment orders.
Does Article 4 apply in Bristol?
Yes. Bristol City Council has Article 4 Directions in force in Clifton and Redland — two of the city's most popular HMO areas. Within these zones, converting a standard dwelling (Use Class C3) to a small HMO (Use Class C4) requires planning permission. Purchasing an existing, licensed HMO in an Article 4 area is generally straightforward for mortgage purposes. The restriction targets new conversions, not established HMOs.
Are Bristol HMO mortgages harder to obtain than in northern cities?
Bristol's higher property values mean that more lenders' maximum loan size caps come into play, and the lower percentage yields require more careful affordability assessment. However, Bristol's very strong and resilient rental demand, low void rates, and quality tenant base make it attractive to specialist HMO lenders. A specialist broker with Bristol market knowledge is essential to access the best rates and lenders for your specific property.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.