.svg)
Student HMO Mortgages: Finance for Student Lets (2026)
Student HMO mortgages for university-area shared houses: how lenders assess term-time lets, licensing and Article 4, and how to apply.
Student HMO Mortgages at a glance
- Max LTV
- 70%
- Indicative rates from
- 5.2%
- Max term
- 25 years
- Typical timeline
- 6-8 weeks
Typically suits borrowers with
- Student property experience preferred
- Understanding of student market
- Professional management setup
Indicative figures; the rate and terms you're offered depend on your circumstances and the property.
Student HMO mortgages explained
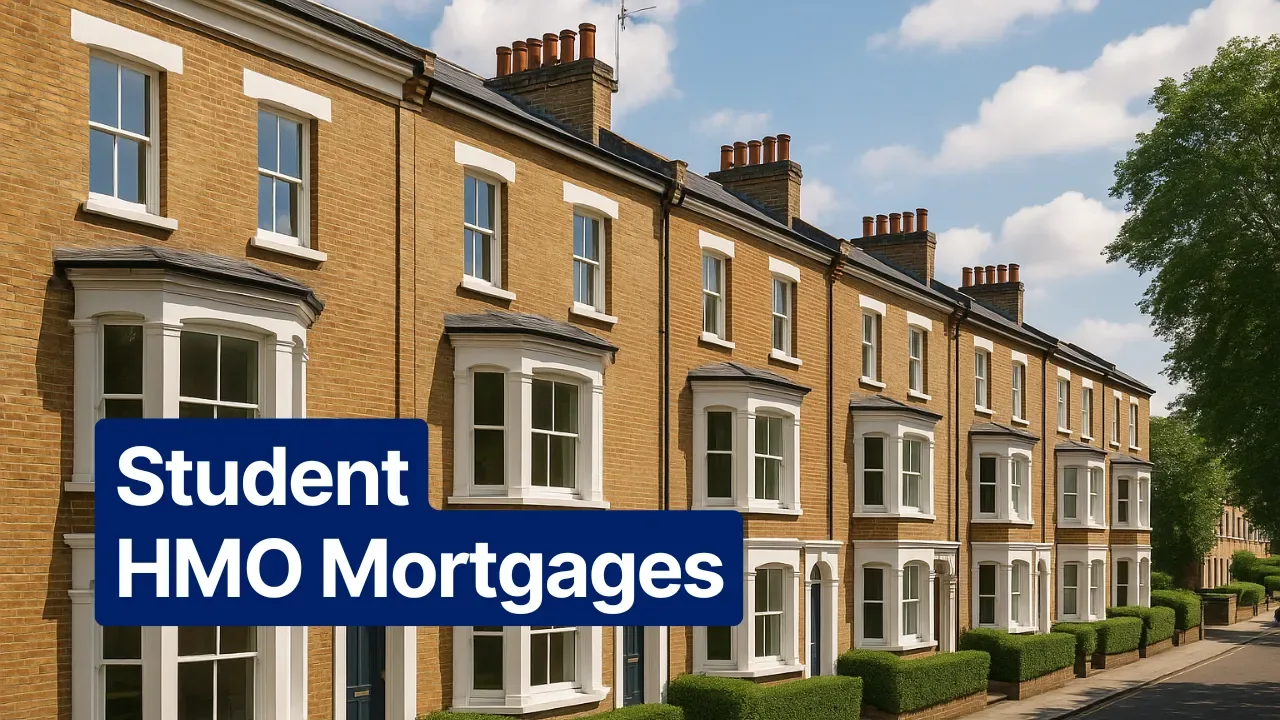
A student HMO mortgage is a specialist loan on a house let to students who share kitchens or bathrooms. Lenders treat it as an HMO, not as a standard buy-to-let, because occupancy follows the academic year, rooms are often let individually, and university-town licensing and Article 4 rules are common. It is the usual product for a shared student house. It is not a residential mortgage for a student buyer, and it is not automatically the same as finance for a purpose-built student block. Compare it with other HMO mortgages once the house type is clear.
What is a student HMO?
A student HMO is a house (or flat) occupied by students who form more than one household and share a basic amenity. Three unrelated students sharing a kitchen is usually an HMO under the Housing Act tests. Five or more occupiers generally need a mandatory HMO licence in England; many university councils also licence three- and four-person houses. Students are not a special household just because they study together. Couples within the house are one household between themselves; the remaining unrelated occupiers still create multiple households.
How lenders assess student lets
Underwriters look at location relative to the campus or a well-used bus route, comparable room rents, the tenancy structure, and how you cover the summer. They haircut rent for voids more aggressively than on a year-round professional HMO. A house that only lets for 39 weeks needs a rent schedule that still passes the interest-cover test on that shorter income, or a 44–51 week contract that you can evidence locally.
Academic-year tenancies
Most student lets run from late summer or September to the following June or July. Some agents now use 44- or 51-week terms. Lenders want to know which pattern you will use and whether the local market actually takes it. A 51-week term on paper does not help if every comparable house is empty in July.
Joint vs room-by-room
A joint AST puts all students on one contract. Room-by-room (or individual licences) gives a rent stream per occupier and more void risk if one room is empty. Some lenders prefer joint contracts; others will take room-by-room if the house is licensed and professionally managed. Say which model you will use before they instruct the valuer.
Guarantors
UK-based parental guarantors are common on student tenancies. They are a management tool, not a substitute for HMO underwriting. The mortgage still stands on the property, the licence and the stressed rent, not on a parent’s salary.
Criteria: deposit, ICR, experience
Plan for a 25% deposit (75% LTV) on a licensed student house. Some lenders go lower LTV in weaker postcodes or for first-time student landlords. Interest cover is tested on the rents the valuer accepts after a void assumption. Landlord experience of about 12 months helps; a few specialists take first-time landlords with a professional agent. Do not model an 85% student HMO unless a named product will take it.
Licensing and Article 4 in university towns
University cities are where additional licensing and Article 4 cluster. Check both before you bid. A licence does not grant C4 use, and C4 use does not grant a licence. Nottingham, Manchester, Oxford and many others run city-wide or ward-level Article 4 on small HMOs. The HMO licence guide and the Article 4 guide cover the tests; this page only flags that student streets are the usual place they bite.
Valuation of student HMOs
Small licensed student houses are often valued on a bricks-and-mortar basis with a cross-check on room rents. Larger or purpose-built stock is more likely to be valued on income. A valuer will look at comparable student lets, not at professional HMOs two postcodes away. Undersized rooms and unlicensed occupancy are stripped out of the rent. That is why the brochure bedroom count is not the mortgage bedroom count.
Purpose-built vs house-share student lets
A terraced house-share is the classic student HMO mortgage. Purpose-built student accommodation (PBSA) is a different asset: often commercial or specialist student finance, nomination agreements, and a different valuer. Do not assume an HMO product designed for a six-bed terrace will fund a 200-bed block. If you mean PBSA, say so at enquiry so we do not send it to a house-share panel.
Risks: voids, summer income, management
Summer voids, late arrivals, higher wear, and agent fees on a bills-inclusive rent are the usual cash-flow risks. Management is more intensive than a single AST: check-ins, deposits, and a new cycle every year. A poor agent in a saturated street will cost more than 0.25% on rates. Student demand also moves with university intake — that is a location risk, not a rate risk.
How to apply
Put the licence position, planning use, tenancy model and a room-by-room rent schedule in the pack with the usual ID, experience and company documents. We then match a specialist student-let lender rather than a generic BTL panel. There is no charge for an initial quote.
Get a student HMO quote
Check how this affects your HMO mortgages enquiry. Tell us it is a student let so we do not send a year-round professional case to the wrong panel.
Related reading: HMO mortgages and HMO licence.
Student HMO Mortgages Calculators
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .
Student HMO Mortgages FAQs
How much are student living expenses?
That depends on the city and the tenancy (bills-inclusive or not). It is not an HMO underwriting figure. Lenders look at room rent and voids, not a student's weekly budget.
David Sampson · Updated 22 October 2026
How to find accommodation in the UK?
Students usually use university housing lists, local agents and portals. This page is about financing a student HMO as a landlord, not about finding a room to rent.
David Sampson · Updated 22 October 2026
What is the 2% rule for renting?
A rule of thumb some investors use (monthly rent around 2% of price). It is not a UK lending test and many viable student HMOs will not meet it.
David Sampson · Updated 22 October 2026
Can a student get a mortgage in the UK?
A student HMO mortgage is a landlord product on a shared student house. It is not a residential mortgage for a student buyer.
David Sampson · Updated 22 October 2026
Do student loans get wiped after 25 years in the UK?
Student-loan write-off rules are a government student-finance question, not an HMO mortgage condition.
David Sampson · Updated 22 October 2026
Can I get a 200k mortgage on 40k salary?
HMO affordability is mainly rental interest cover, not a residential income multiple. A £40k salary does not set a £200k HMO loan by itself.
David Sampson · Updated 22 October 2026
What is a student HMO?
A house or flat occupied by students who form more than one household and share a kitchen, bathroom or toilet. It is usually an HMO under the Housing Act tests.
David Sampson · Updated 22 October 2026
Can I get a buy-to-let mortgage for a student HMO?
You need a specialist HMO or student-let product, not a standard single-let buy-to-let, once more than one household shares facilities.
David Sampson · Updated 22 October 2026
Do student lets need an HMO licence?
Often yes. Five or more occupiers usually need a mandatory licence in England, and many university councils also licence smaller houses.
David Sampson · Updated 22 October 2026
Which lenders do student let mortgages?
Specialist HMO lenders that accept student tenants. Compare the lenders hub; high-street single-let products usually will not fit.
David Sampson · Updated 22 October 2026
How are student HMOs valued?
Small licensed houses are often bricks-and-mortar with a rent cross-check. Larger or purpose-built stock is more likely to be valued on income.
David Sampson · Updated 22 October 2026
What deposit do I need for a student HMO?
Plan for 25% (75% LTV). Weaker postcodes or first-time student landlords can need more.
David Sampson · Updated 22 October 2026
What is a student HMO mortgage?
A student HMO mortgage funds properties let to students, usually per-room on joint ASTs or similar, often near universities. Lenders apply specialist criteria: academic-year void assumptions, higher wear and tear, and sometimes minimum room numbers. Yields can be strong, but management intensity is higher than professional lets. Licensing and Article 4 restrictions are common in university cities.
David Sampson · Updated 23 November 2025
How do student HMO mortgages differ from standard HMOs?
Lenders may cap LTV slightly lower, require evidence of student demand (proximity to university), and stress rents with summer void periods. Some insist on experienced landlords or professional management. Rates are broadly in line with standard HMO products but the lender panel is smaller. Room layouts must still meet HMO minimum sizes and fire standards.
Milly Turner · Updated 17 May 2026
CeMAP Qualified
CeMAP (Certificate in Mortgage Advice and Practice)
6+ years mortgage industry experience
Arranged £50M+ in HMO lending
1,200+ clients helped
Portfolio Expansion Specialist
HMO Mortgages
Portfolio Finance
First-Time Landlords
Buy-to-Let
HMO Finance Specialist
Portfolio Management Specialist
New Landlord Advisor
About the author
Milly is a senior HMO mortgage adviser with extensive experience in property finance and portfolio management.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .