.svg)
Commercial HMO Mortgages
Commercial HMO mortgages: when a house needs commercial lending, income valuation, deposit and LTV, limited-company borrowing and how to apply.
Commercial HMO Mortgages at a glance
- Typical timeline
- 6-8 weeks
Typically suits borrowers with
- HMO or commercial experience preferred on larger stock
- Professional management often required
- Deposit typically 25% (75% LTV) unless a named product says otherwise
Indicative figures; the rate and terms you're offered depend on your circumstances and the property.
Commercial HMO mortgages explained
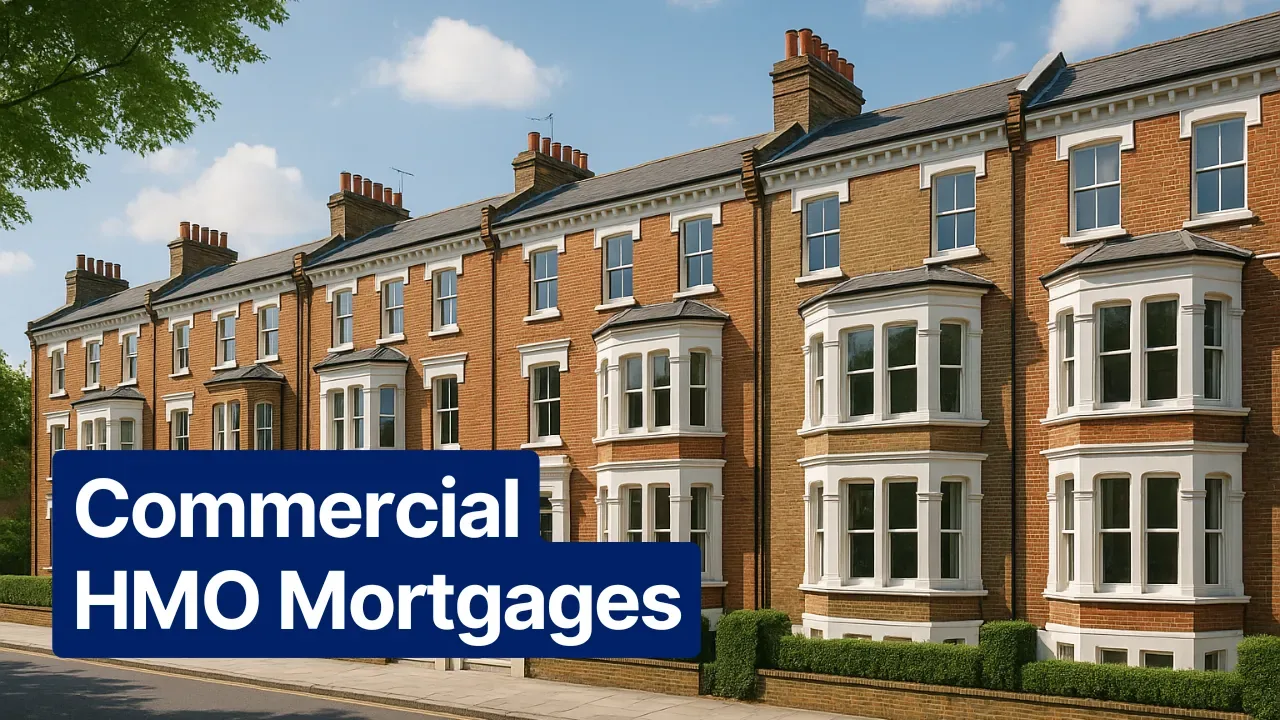
A commercial HMO mortgage is a loan on a house in multiple occupation that a specialist or commercial lender treats as an income-producing asset rather than a house-share buy-to-let. The usual triggers are an income valuation, sui generis planning, a high unit count, mixed commercial/residential use, or a borrower already on a commercial facility. It is still an HMO finance product. Compare it with other HMO mortgages and with large HMO mortgages once the room count and valuation basis are clear.
Commercial finance for an HMO is not a published £1 million minimum and it is not a different legal definition of an HMO. The house is still an HMO in housing law. The loan is what changes. There is no unsourced “from 5.8%” on this page. Ask for a dated illustration.
Can you get a mortgage on an HMO property? Yes — on the right wrapper. A small licensed house uses the specialist HMO panel. A commercially valued multi-let uses this page. Is it hard? Harder than a four-bed C4 because the panel is smaller and the valuation pack is heavier. A licensed, well-evidenced income case is still routine for the right lender.
When an HMO needs commercial lending
Room count alone does not flip the case. The combination does.
| What you have | Typical valuation | Typical wrapper |
|---|---|---|
| 3–6 bed licensed C4, personal or SPV | Bricks-and-mortar, rent cross-check | Specialist HMO / BTL panel |
| 7+ occupier sui generis, or 10+ rooms | More often income | Narrower HMO panel or commercial |
| Mixed-use (shop with rooms above) or large multi-let | Commercial / investment | Commercial or semi-commercial |
| Portfolio already on commercial facilities | As the existing lender instructs | Often stay commercial |
A 6 bed C4 on a house valuation is usually not a commercial loan. A 12-bed sui generis house valued on yield often is. Confirm before you instruct — see how HMOs are valued.
Commercial (investment) valuation and how it changes borrowing
The surveyor capitalises accepted rent after voids, management and running costs. Loan-to-value is a percentage of that figure. It can sit above or below the vacant-possession comparable. Undersized, unlicensed or unsafe rooms come out of the rent. That is why the brochure bedroom count is not the mortgage bedroom count.
Shawbrook publishes that investment valuations are available on HMOs (own buy-to-let page, checked 22 October 2026). Paragon may use an investment valuation at its discretion. Other lenders decide case by case. You cannot usually pick your own mortgage valuer.
Criteria: deposit, DSCR/ICR, experience
Plan for a 25% deposit (75% LTV) unless a named product’s own page says otherwise. Do not model 85%. Interest cover may be written as ICR or as DSCR (debt-service cover) on a commercial facility. This page does not invent a single percentage. The Mortgage Works publishes 175% ICR for all HMO applications (intermediary HMO criteria, checked 22 October 2026). Other commercial-HMO lenders on our panel do not publish one HMO ICR on the pages cited, so treat cover as “Not published” until the DIP names the test.
Experience matters more as the house gets larger. A first-time landlord on a 12-bed commercial case is a much smaller panel than a first six-bed. Professional management is often required. Limited-company (SPV) borrowing is common and does not replace experience.
How much is a £300,000 mortgage per month? That is a repayment-calculator question, not a commercial-HMO rule. The payment depends on rates on the illustration, interest-only versus repayment, and the fees added to the loan. Use the calculators as a sketch. Current HMO rates for Ltd companies are not a single published figure here.
Commercial vs buy-to-let HMO mortgage
A specialist HMO buy-to-let is still a buy-to-let product: term, LTV bands, and a house or hybrid valuation. A commercial HMO loan uses commercial underwriting: income valuation, sometimes DSCR instead of a simple ICR, sometimes a different legal charge and a shorter or more flexible term. Fees and legal work are usually heavier. Most investment HMO loans are not FCA-regulated in the same way as a home loan; a commercial facility on a mixed-use building can sit in a different regulatory bucket. Say what the building is used for.
Rates on commercial stock are not automatically “more expensive” as a published rule, but the all-in cost (rate plus fees plus a commercial valuation) is often higher than a small C4 HMO on the specialist panel. Compare a dated illustration, not a blog average.
Limited company and portfolio borrowers
SPVs are the usual wrapper for larger commercial HMOs. Director guarantees are normal. A portfolio already on commercial terms may remortgage as a block or property by property. Personal-name commercial HMO loans exist but the panel is narrower. Moving a house from personal name onto a commercial company facility is a sale and a purchase for stamp duty and the lender — budget that before you treat it as a free restructure.
Refinancing onto a commercial valuation
Landlords remortgage onto an income basis when a house that was bought on bricks-and-mortar can now evidence a higher investment figure — after a licence, a sui generis consent, or a rent rise the valuer will accept. That is how some raise capital for the next purchase. Not every remortgage lender will take the new basis. Start with the valuation question, then the product.
Refurbishment and conversion of commercial or sui generis stock usually need a bridge or development loan first. Do not apply for a term commercial HMO mortgage on a shell. A refinance after works uses the finished income figure. If the valuer will not count the new rooms, the commercial uplift you modelled does not exist.
Are commercial HMO mortgages more expensive? The all-in cost is often higher than a small C4 specialist loan because the valuation and legal work cost more. That is not the same as a published higher headline rate. Compare fees and the months to complete as well as rates.
How to apply
Put the licence, planning use, occupancy cap, room-by-room rent, accounts if the house is trading, and floor plans in the pack with ID, experience and company documents. Say you want an income valuation if that is the point of the case. We then match a commercial or specialist HMO lender rather than a four-bed panel. There is no charge for an initial quote. Use the HMO mortgage calculator on this page as a sketch of monthly cost and cover before you apply; the DIP uses the lender’s own test. What are the current mortgage rates for HMOs? There is no unsourced headline on this page — the commercial case is priced after the valuer’s figure, not before it.
Get a commercial HMO quote
Check how this affects your HMO mortgages enquiry. Tell us the bedroom count, the planning use and whether you need an income valuation, so we do not send a six-bed C4 to a commercial desk — or a mixed-use block to a house-share product.
When is commercial HMO finance the right choice?
In short: when the property is (or was) non-residential, has a large number of units, or needs commercial-style underwriting based on cash flow rather than a simple buy-to-let model. Typical examples include former offices, hotels, or mixed-use blocks converted to HMO accommodation. These deals often need planning permission, professional valuations on a commercial basis, and evidence of experienced management.
What to expect from lenders
Commercial HMO mortgages may offer LTV around 65–75% depending on location, tenant demand, and your track record. Rates are often slightly higher than standard residential HMO products because of conversion risk and void periods during works. Lenders will review detailed cash-flow forecasts, fire safety compliance, and whether you use professional HMO management. We compare specialist commercial HMO lenders so you are not limited to high-street banks that decline non-standard assets.
If you are converting from commercial use, confirm Article 4 directions and local planning policy early — lenders will ask for evidence that the change of use is lawful before releasing funds.
Related Resources
Related reading: HMO mortgages, how HMOs are valued and large HMO mortgages.
Commercial HMO Mortgages Calculators
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .
Commercial HMO Mortgages FAQs
Can I get a mortgage on an HMO property?
Yes — on the right wrapper. A small licensed house uses the specialist HMO panel. A commercially valued multi-let uses a commercial HMO mortgage. The house is still an HMO in housing law; the loan is what changes.
David Sampson · Updated 22 October 2026
Is it hard to get a HMO mortgage?
Harder than a four-bed C4 because the commercial panel is smaller and the valuation pack is heavier. A licensed, well-evidenced income case is still routine for the right lender.
David Sampson · Updated 22 October 2026
Are HMO mortgages more expensive?
Specialist HMO products often price above vanilla single-let buy-to-let because underwriting and valuation cost more. That is not a published commercial-HMO headline rate. Compare a dated illustration, including fees.
David Sampson · Updated 22 October 2026
What are the current mortgage rates for HMOs?
There is no unsourced headline rate on this page. A commercial HMO case is priced after the valuer’s income figure, not before it. Ask for a dated illustration.
David Sampson · Updated 22 October 2026
How much is a 300k mortgage per month in the UK?
That is a repayment-calculator question, not a commercial-HMO rule. The payment depends on the rate on the illustration, interest-only versus repayment, and the fees added to the loan. Use the calculators as a sketch.
David Sampson · Updated 22 October 2026
What are the current HMO mortgage rates for Ltd companies?
Current HMO rates for Ltd companies are not a single published figure here. A company commercial HMO loan is priced on LTV, the income valuation and the current rent roll. Ask for a dated illustration.
David Sampson · Updated 22 October 2026
What is a commercial HMO mortgage?
A loan on a house in multiple occupation that a specialist or commercial lender treats as an income-producing asset rather than a house-share buy-to-let. It is still an HMO finance product, not a different legal definition of an HMO.
David Sampson · Updated 22 October 2026
When does an HMO need a commercial mortgage?
Usually when the valuer uses an income basis, the house is sui generis or mixed-use, the unit count is high, or the borrower is already on a commercial facility. Room count alone does not flip the case.
David Sampson · Updated 22 October 2026
How is a commercial HMO valued?
The surveyor capitalises accepted rent after voids, management and running costs. Loan-to-value is a percentage of that figure. Undersized, unlicensed or unsafe rooms come out of the rent.
David Sampson · Updated 22 October 2026
Are commercial HMO mortgages more expensive?
The all-in cost is often higher than a small C4 specialist loan because the valuation and legal work cost more. That is not the same as a published higher headline rate. Compare fees and the months to complete as well as the rate.
David Sampson · Updated 22 October 2026
Can I refinance an HMO on a commercial valuation?
Sometimes. Landlords remortgage onto an income basis when a house that was bought on bricks-and-mortar can now evidence a higher investment figure. Not every remortgage lender will take the new basis.
David Sampson · Updated 22 October 2026
What is an HMO mortgage?
An HMO mortgage is a specialist buy-to-let loan for a house in multiple occupation, where three or more people from more than one household share facilities. Lenders underwrite the combined room rents, licence position and valuation method rather than a single tenancy. Most high-street buy-to-let products do not cover this, so the case usually goes to a specialist lender.
David Sampson · Updated 21 October 2026
How much deposit do I need for an HMO mortgage?
Many specialist lenders offer up to 75% LTV on a small, licensed HMO, which means a deposit of around 25% of the valuation or purchase price. Larger HMOs, first-time landlords and pending-licence cases are often asked for more. The deposit is only one test: the rental stress test still has to pass on the room rents.
Milly Turner · Updated 21 October 2026
Can I get an HMO mortgage with no experience?
Some specialist lenders will consider a first HMO with no prior landlord experience if the deposit, location, licence plan and management arrangements are clear. Others want around 12 months of HMO or buy-to-let management. A professional managing agent and a property that already meets room-size and fire standards usually widens the panel.
Sarah Johnson · Updated 21 October 2026
CeMAP Qualified
CeMAP (Certificate in Mortgage Advice and Practice)
4+ years development finance experience
Arranged £25M+ in development finance
Development Finance Specialist
Development Finance
HMO Conversions
Commercial Finance
Refurbishment Loans
Development Finance Specialist
HMO Conversion Specialist
Commercial Property Advisor
About the author
Sarah specializes in HMO development finance and commercial property solutions.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .