.svg)
Expat HMO Mortgages | UK Property Finance from Abroad (2026)
Build your UK property empire from anywhere with expat HMO mortgages. Accept foreign currency income and access rates from 5.7% with remote processing.
Expat HMO Mortgages at a glance
- Max LTV
- 70%
- Indicative rates from
- 5.7%
- Max term
- 25 years
- Typical timeline
- 6-8 weeks
Typically suits borrowers with
- UK citizen or eligible expat
- Stable overseas employment
- Good credit history
Indicative figures; the rate and terms you're offered depend on your circumstances and the property.
What are Expat HMO Mortgages?
An expat HMO mortgage lets UK nationals living abroad, and eligible foreign nationals, buy or refinance an HMO in the UK while living overseas. Specialist lenders accept stable overseas employment income, usually ask for a deposit of at least 30%, and expect the property to be licensed and professionally managed, since you cannot run it day to day yourself.
These specialist products address the unique challenges faced by expat borrowers, including foreign income verification, currency considerations, and remote property management.
Challenges for Overseas HMO Investors
Investing in UK HMO properties from overseas presents several unique challenges. Currency fluctuations can affect both your initial investment and ongoing rental income, making financial planning more complex.
Tax implications vary depending on your country of residence, and you may be subject to tax in both the UK and your country of residence. Property management from abroad is particularly challenging for HMO properties, which require more active management than standard buy-to-let properties. This makes professional property management essential for expat investors.
Expat HMO Mortgage Criteria
Lenders who offer expat HMO mortgages typically accept income in foreign currencies and understand international employment structures.
The application process often involves video calls and electronic document submission due to the borrower's overseas location. Expat HMO mortgages typically require larger deposits (typically 25-30%) and may have slightly higher interest rates to offset the perceived additional risk.
Most lenders will require evidence that you have professional management in place before approving finance. You'll typically need to provide proof of income, which may need to be converted to GBP, and demonstrate your ability to service the mortgage from overseas.
However, they provide an excellent opportunity for expats to build UK property portfolios and benefit from rental income while living abroad, often serving as a pathway for future UK repatriation.
Expats investing in the UK should understand the tax rules for overseas landlords to remain compliant.
Can UK expats get HMO mortgages while living abroad?
In short: yes — specialist lenders accept UK expats and some foreign nationals, provided income, identity, and rental income are documented clearly. You will usually need a UK-based HMO management company, UK bank accounts for rent collection, and evidence that you can meet repayments from overseas employment or business income.
Currency, tax, and documentation
Lenders may apply exchange-rate haircuts on foreign income and request translated or apostilled documents. Tax residency in your country of residence can affect how profits are treated, so cross-border advice is important before purchase. Deposits often must be traceable to UK or international bank accounts with clear source-of-funds evidence. We match expat clients to lenders familiar with overseas earners rather than mainstream buy-to-let panels that decline non-UK residents.
Other HMO Mortgage Types
Explore our other specialist solutions, or return to the hub for HMO mortgages.
Key Features of Expat HMO Mortgages
Global Income
Accept income from worldwide employment or business.
Currency Flexibility
Income in foreign currencies considered.
Expat Specialists
Lenders who understand expat circumstances.
UK Investment
Build a UK property portfolio while living abroad.
Remote Processing
Application process managed remotely with video calls.
Tax Efficiency
Advice on UK tax implications for expat landlords.
Expat HMO Mortgages Eligibility Requirements
Understanding eligibility requirements helps you prepare a successful application. Our specialist lenders assess applications based on both property characteristics and borrower circumstances, with flexibility for experienced investors and first-time landlords alike. While these are general guidelines, many lenders offer flexible criteria. Our brokers work with specialist lenders who understand HMO investments and can find solutions even if you don't meet every requirement.
Property requirements
- Yes:UK-based HMO propertyExpat mortgages typically require UK-based properties. Lenders need to verify the property location and ensure it meets UK HMO standards.
- Yes:Professional management arrangedSome lenders require professional property management, especially for large HMOs or first-time landlords. This ensures compliance and proper tenant management.
- Yes:Good rental locationProperties in areas with good transport links, local amenities, and strong rental demand typically receive more favourable lending terms.
- Yes:Valid HMO licensingProperties requiring an HMO licence must have valid licensing in place before mortgage completion. Unlicensed properties may not be eligible.
Borrower requirements
- Yes:UK citizen or eligible expatExpat HMO mortgages are available to UK citizens living abroad or eligible expatriates. Lenders assess your eligibility based on nationality, residency status, and employment.
- Yes:Stable overseas employmentExpat lenders require evidence of stable employment overseas, typically through employment contracts and payslips. This demonstrates your ability to service the mortgage.
- Yes:Good credit historyCredit history requirements vary by product type. Most lenders look for good credit, though some specialist products may be more flexible.
- Yes:Minimum 30% depositDeposit requirements vary by product type and lender. Most HMO products require 25-30% deposit, though some specialist products may require higher deposits.
Common eligibility questions
What if I don't have landlord experience?
Many lenders accept first-time landlords, especially if you have a strong financial position, professional property management arrangements, or relevant business experience. Our brokers can help identify lenders suitable for your situation.
What credit score do I need for expat hmo mortgages?
Most lenders look for good credit history, though some specialist lenders may consider cases with minor credit issues. Recent defaults or CCJs may limit your options, but we work with lenders who specialise in adverse credit cases.
Can I get a mortgage with less than 25% deposit?
While 25% deposit is standard, some lenders may offer up to 80% LTV (20% deposit) for experienced landlords with strong portfolios. Our brokers can assess your specific situation and identify lenders offering higher LTV options.
What if my property doesn't have an HMO licence yet?
Properties requiring an HMO licence must have valid licensing before mortgage completion. If you're purchasing a property that needs licensing, we can help coordinate the application process and work with lenders who understand HMO licensing requirements.
Expat HMO Mortgages Process
Our mortgage process, step by step.
- 1
Expat HMO Consultation
45 minutes - 2
Expat Application Process
2-3 days - 3
Expat Property Valuation
1-2 weeks - 4
Expat Underwriting
3-4 weeks - 5
Expat Legal Process
2-4 weeks - 6
Expat Completion
Same day
Expat HMO Mortgages Calculators
Current Expat HMO Mortgages Rates
Live rates from our specialist lenders for expat hmo mortgages. Monthly payments shown are calculated using a representative example of £250,000 loan amount.
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .
Expat HMO Mortgages Success Stories
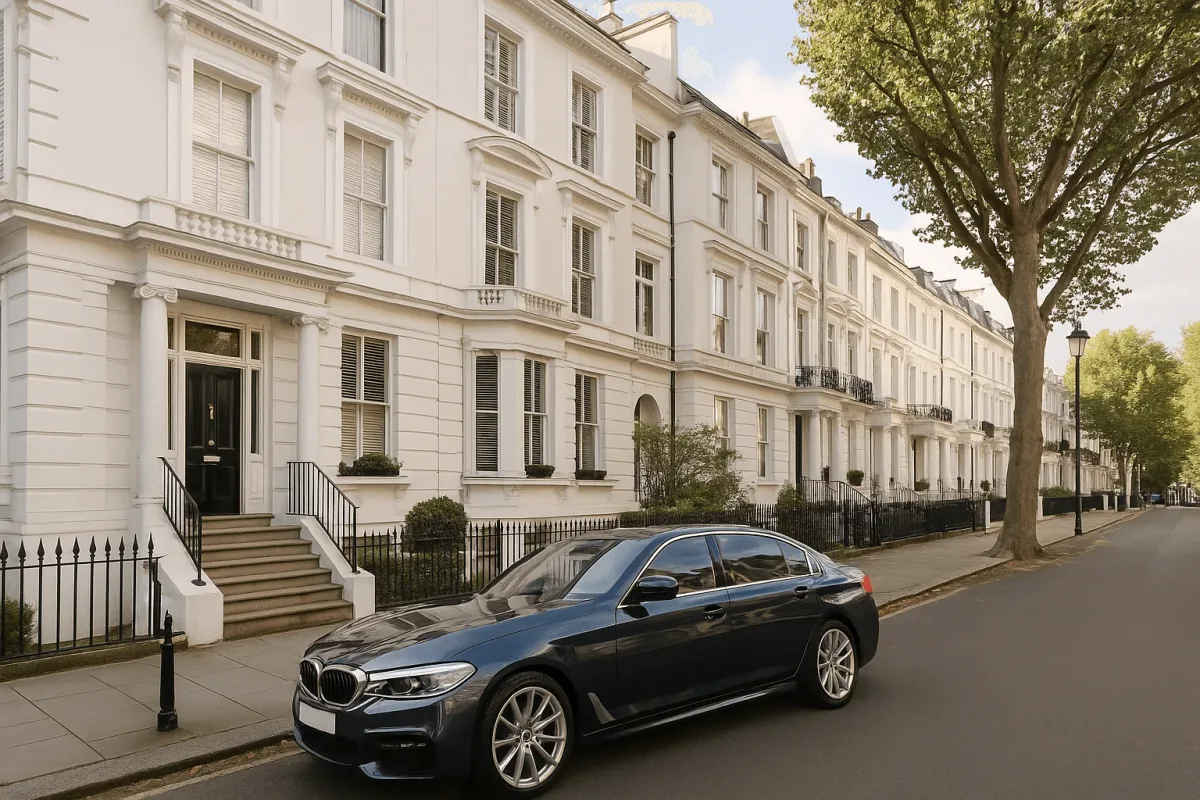
London · £595K · 10 weeks
Expat HMO Investment in London
Assisted an expat investor in securing financing for a premium HMO property in London's Zone 2.
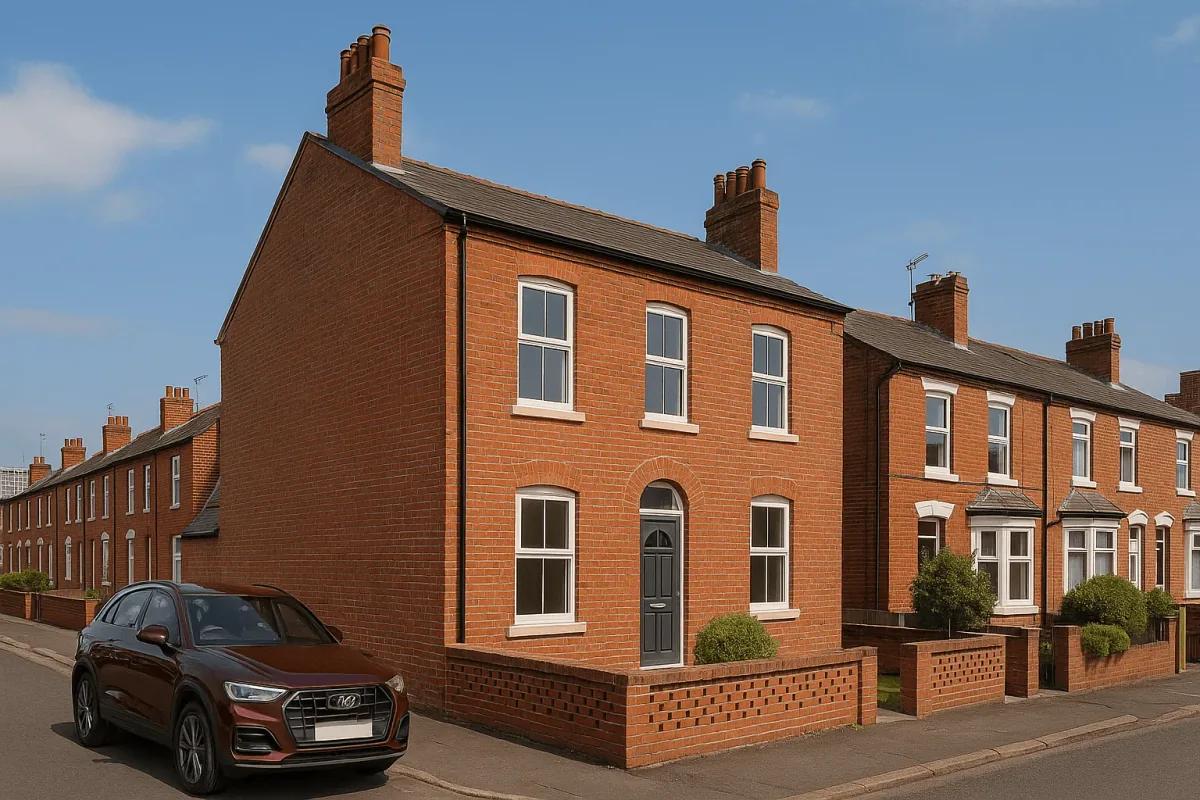
Manchester · £294K · 8 weeks
Dubai-Based Investor's Manchester HMO
Arranged expat HMO mortgage for Dubai-based investor purchasing their first UK HMO property.
Expat HMO Mortgages Fees Guide
Typical costs involved with expat hmo mortgages.
Arrangement Fee1% - 2.5%
- Paid to:
- Expat Lender
- When:
- Completion
Fee charged by specialist expat lenders for HMO mortgages. Covers additional complexity of overseas income assessment.
Valuation Fee£400 - £1,000
- Paid to:
- UK Surveyor
- When:
- Application
Professional UK property valuation. May require local surveyor due to borrower being overseas.
Legal Fees£800 - £2,000
- Paid to:
- UK Solicitor
- When:
- Completion
UK legal costs including overseas income verification and additional compliance for expat borrowers.
Currency Exchange Fee0.5% - 2%
- Paid to:
- Bank/Exchange
- When:
- Various
Costs associated with currency conversion for overseas income and deposit transfers.
Broker Fee0.75% - 1.5%
- Paid to:
- Expat Broker
- When:
- Completion
Fee for arranging expat HMO mortgage. Specialist expat knowledge commands premium fees.
Document Verification£200 - £500
- Paid to:
- Verification Service
- When:
- Application
Cost of verifying overseas employment and income documentation. May require translation and apostille services.
Expat HMO Mortgages FAQs
Can expats get HMO mortgages?
Yes — UK expats and some foreign nationals can access specialist expat HMO mortgages. Lenders verify overseas income, may require UK bank accounts, and often need larger deposits (30–35%). Time-zone and document certification requirements apply. A broker with expat panel knowledge is important because high-street banks rarely offer HMO expat products.
David Sampson · Updated 17 May 2026
What documents do expats need for HMO mortgages?
Typically: certified passport and proof of address overseas, employment contract or business accounts, payslips or tax returns, bank statements (sometimes translated), proof of deposit source, and UK property details including HMO licence and rent schedule. Some lenders want a UK-based accountant or lawyer. Documents usually need solicitor or notary certification.
Milly Turner · Updated 5 April 2026
How do expat HMO mortgage rates compare?
Expat HMO rates are often 0.5–1.5% above UK-resident specialist HMO products, with 70% LTV a common cap. Strong income in sterling or major currencies, larger deposits, and experienced landlords improve pricing. The spread has narrowed as more specialist lenders compete for expat landlord business.
Sarah Johnson · Updated 17 May 2026
What are the typical requirements for expat HMO mortgages?
Certified ID, overseas income evidence, larger deposit (often 30–35%), UK bank account in many cases, acceptable property and licence, and sometimes UK-based accountant references. Currency and country risk lists apply — not all jurisdictions are accepted.
David Sampson · Updated 12 April 2026
What deposit do expats need for HMO mortgages?
Typically 30–35% for expat specialist products, with 70% LTV a common ceiling. Sterling earners or major-currency income may access better terms. Larger deposits widen lender choice and reduce rate premiums.
Milly Turner · Updated 17 May 2026
Do I need a UK bank account for an expat HMO mortgage?
Most lenders require a UK bank account for expat HMO mortgages, though some may accept international accounts if you have a UK-based property manager. This helps with rental income management and mortgage payments.
Sarah Johnson · Updated 15 March 2026
How do I prove my overseas income for an HMO mortgage?
You'll need translated payslips, bank statements, employment contracts, and potentially tax returns. Some lenders may require income verification through international agencies, which can add 2-4 weeks to the application process.
David Sampson · Updated 26 April 2026
Can I get an HMO mortgage if I'm not a UK citizen?
Some lenders accept non-UK citizens with residency or investor visas, or overseas nationals buying through appropriate structures — criteria vary widely. You will need certified documents, often a larger deposit, and a specialist broker. British expats are usually treated under expat products with different document rules.
Milly Turner · Updated 10 May 2026
How long does an expat HMO mortgage application take?
Allow 6–10 weeks due to overseas document certification and income verification. Strong preparation (certified translations, clear deposit trail) can shorten timelines. Time zones can slow communication with lenders — respond promptly to information requests.
Sarah Johnson · Updated 17 May 2026
What are the tax implications for expat HMO landlords?
You may owe UK income tax on UK rental profits and potentially tax in your country of residence. Double-tax treaties may give relief. Non-resident landlords often register under the NRL scheme with letting agents deducting tax unless HMRC approval is obtained. Take cross-border tax advice before purchase.
David Sampson · Updated 17 May 2026
Expat HMO Mortgages Key Terms
- Expat MortgageA specialist mortgage for UK citizens living and working abroad who wish to invest in UK property like an HMO.
- Overseas IncomeIncome earned outside the UK, which may be considered differently by lenders when assessing mortgage applications.
- Expat DocumentationThe paperwork required for expat mortgage applications, including proof of income, residency, and property management experience.
- Currency ExchangeThe conversion of foreign currency to British pounds, relevant for expat mortgage applications where income is earned overseas.
CeMAP Qualified
DipFA
CeMAP (Certificate in Mortgage Advice and Practice)
DipFA (Diploma in Financial Advice)
15+ years mortgage industry experience
Arranged £187M+ in HMO lending
4,000+ clients helped
Founded The HMO Mortgage Broker
HMO Mortgages
Development Finance
Portfolio Lending
Commercial Finance
HMO Finance Specialist
Property Investment Specialist
About the author
David is the founder and senior HMO mortgage specialist with over 15 years of experience in property finance. He founded the firm in 2013, which has since helped 4,000+ landlords secure HMO finance.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.