.svg)
HMO Mortgage for Ltd Company: Criteria & LTV (2026)
Maximise HMO returns with tax-efficient limited company mortgages. Pay corporation tax instead of higher personal rates and protect your assets through a specialist limited-company structure.
Limited Company HMO Mortgages at a glance
- Typical timeline
- 6-8 weeks
Typically suits borrowers with
- UK registered limited company
- Directors with good credit
- Property investment experience
Indicative figures; the rate and terms you're offered depend on your circumstances and the property.
What are Limited Company HMO Mortgages?
Limited Company HMO mortgages are specialist financing products for property investors who wish to purchase and operate HMO properties through a corporate structure rather than personally. They sit alongside personal-name HMO mortgages on a specialist panel. Transferring a house into a company can trigger stamp duty and capital gains — use the HMO stamp duty calculator as a planning tool and take accountant advice before you move title.
These mortgages offer significant tax advantages, including corporation tax rates (typically lower than higher-rate personal tax), the ability to claim mortgage interest as a business expense, and opportunities for tax-efficient profit extraction through dividends.
Tax Advantages of Limited Company Ownership
Limited company ownership provides substantial tax benefits for HMO investors. Corporation tax rates are currently lower than higher-rate personal tax, meaning you can retain more of your rental income within the company.
Additionally, mortgage interest can be claimed as a business expense, reducing your taxable profit. This is particularly valuable given that personal landlords can no longer fully deduct mortgage interest from their rental income. You can also extract profits tax-efficiently through dividends, potentially saving thousands of pounds annually compared to personal ownership.
Limited company ownership also provides asset protection through limited liability, separating business and personal assets.
Setting Up a Limited Company for HMO Investment
The mortgage application process considers the company's financial position, director guarantees, and the property's rental potential.
Many investors use Special Purpose Vehicles (SPVs) - companies created specifically to hold property investments - which can provide cleaner corporate structures and facilitate portfolio growth. SPVs are often preferred by lenders as they demonstrate a clear investment purpose and make it easier to assess the company's financial position.
When applying for a limited company HMO mortgage, lenders will typically require director guarantees, review the company's accounts, and assess the property's rental income potential. The process is similar to personal mortgages but requires additional corporate documentation.
Many landlords choose to purchase through a corporate structure—here's how to set up a limited company according to UK guidelines.
Who should use a limited company HMO mortgage?
In short: higher-rate taxpayers, portfolio builders using SPVs, and investors who want full mortgage interest relief after Section 24 restrictions on personal landlords. It is often less suitable for basic-rate taxpayers with one or two properties unless you plan significant growth. Many investors incorporate before their first purchase; others transfer later, which involves stamp duty, lender consent, and legal costs that must be modelled carefully with your accountant.
Typical rates, LTV, and what lenders check
Limited company HMO loan-to-value is often up to 75% for established SPVs and 70% for newly formed companies. Current pay rates sit on the dated HMO rates page rather than as a single headline figure. Lenders stress-test rental income at roughly 125–145% of mortgage payments and usually require director personal guarantees. You will need company accounts or accountant certificates, proof of rental income, valid HMO licensing, and a clear SPV structure. Compare live options or request a tailored quote.
Related reading: HMO mortgages and HMO stamp duty calculator.
Other HMO Mortgage Types
Explore our other specialist solutions, or return to the hub for HMO mortgages.
Key Features of Limited Company HMO Mortgages
Tax Efficiency
Take advantage of corporation tax rates and allowable expenses.
Asset Protection
Limited liability protection for your property portfolio.
Company Lending
Mortgages in the company name, not personal guarantees.
Portfolio Growth
Scalable structure for building a larger HMO portfolio.
Professional Setup
Support with SPV company setup and structure.
Market-Leading Rates
Access to specialist limited company HMO rates.
Limited Company HMO Mortgages Eligibility Requirements
Understanding eligibility requirements helps you prepare a successful application. Our specialist lenders assess applications based on both property characteristics and borrower circumstances, with flexibility for experienced investors and first-time landlords alike. While these are general guidelines, many lenders offer flexible criteria. Our brokers work with specialist lenders who understand HMO investments and can find solutions even if you don't meet every requirement.
Property requirements
- Yes:HMO suitable propertyThe property must be suitable for HMO use, with adequate space, appropriate layout, and potential for multiple occupancy. Lenders assess the property's suitability for HMO conversion or operation.
- Yes:Strong rental yield potentialLenders assess rental yield potential through local market analysis and property characteristics. Higher yields (typically 8%+) improve your chances of approval and may access better rates.
- Yes:Good location and conditionProperties in areas with good transport links, local amenities, and strong rental demand typically receive more favourable lending terms.
- Yes:Minimum property value £150kSome lenders set minimum property values to ensure sufficient security. Higher-value properties may access better rates and terms.
Borrower requirements
- Yes:UK registered limited companyLimited company HMO mortgages require a UK-registered company structure, typically a Special Purpose Vehicle (SPV) set up specifically for property investment.
- Yes:Directors with good creditCredit history requirements vary by product type. Most lenders look for good credit, though some specialist products may be more flexible.
- Yes:Property investment experienceExperience requirements vary by product type. Some specialist products are more flexible with experience, while others require proven track records.
- Yes:Minimum 25% company depositDeposit requirements vary by product type and lender. Most HMO products require 25-30% deposit, though some specialist products may require higher deposits.
Common eligibility questions
What if I don't have landlord experience?
Many lenders accept first-time landlords, especially if you have a strong financial position, professional property management arrangements, or relevant business experience. Our brokers can help identify lenders suitable for your situation.
What credit score do I need for limited company hmo mortgages?
Most lenders look for good credit history, though some specialist lenders may consider cases with minor credit issues. Recent defaults or CCJs may limit your options, but we work with lenders who specialise in adverse credit cases.
Can I get a mortgage with less than 25% deposit?
While 25% deposit is standard, some lenders may offer up to 80% LTV (20% deposit) for experienced landlords with strong portfolios. Our brokers can assess your specific situation and identify lenders offering higher LTV options.
What if my property doesn't have an HMO licence yet?
Properties requiring an HMO licence must have valid licensing before mortgage completion. If you're purchasing a property that needs licensing, we can help coordinate the application process and work with lenders who understand HMO licensing requirements.
Limited Company HMO Mortgages Process
Our mortgage process, step by step.
- 1
Limited Company Consultation
45 minutes - 2
Corporate Application Process
2-3 days - 3
Corporate Property Valuation
1-2 weeks - 4
Corporate Underwriting
3-4 weeks - 5
Corporate Legal Process
2-4 weeks - 6
Corporate Completion
Same day
Limited Company HMO Mortgages Calculators
Current Limited Company HMO Mortgages Rates
Live rates from our specialist lenders for limited company hmo mortgages. Monthly payments shown are calculated using a representative example of £250,000 loan amount.
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .
Limited Company HMO Mortgages Success Stories
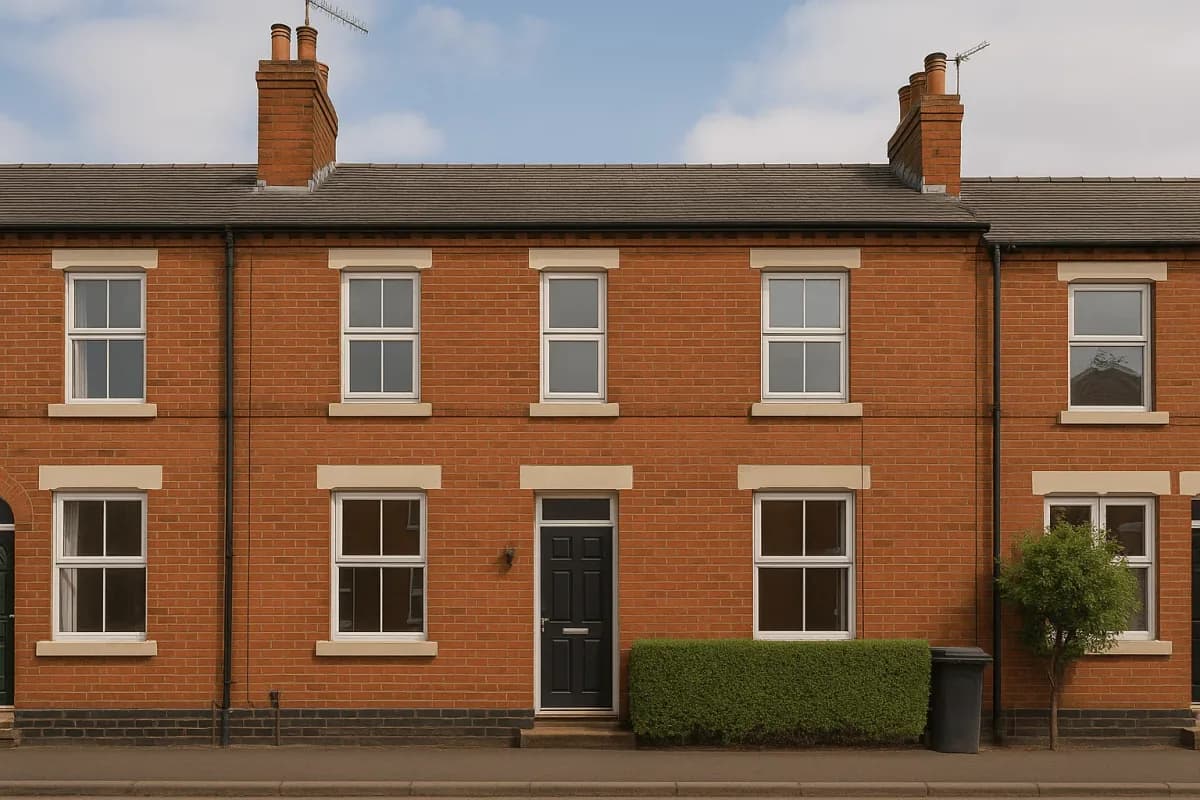
Manchester · £338K · 6 weeks
£450k Limited Company HMO in Manchester
Helped a property investor secure competitive financing for a 6-bedroom HMO through their limited company structure.
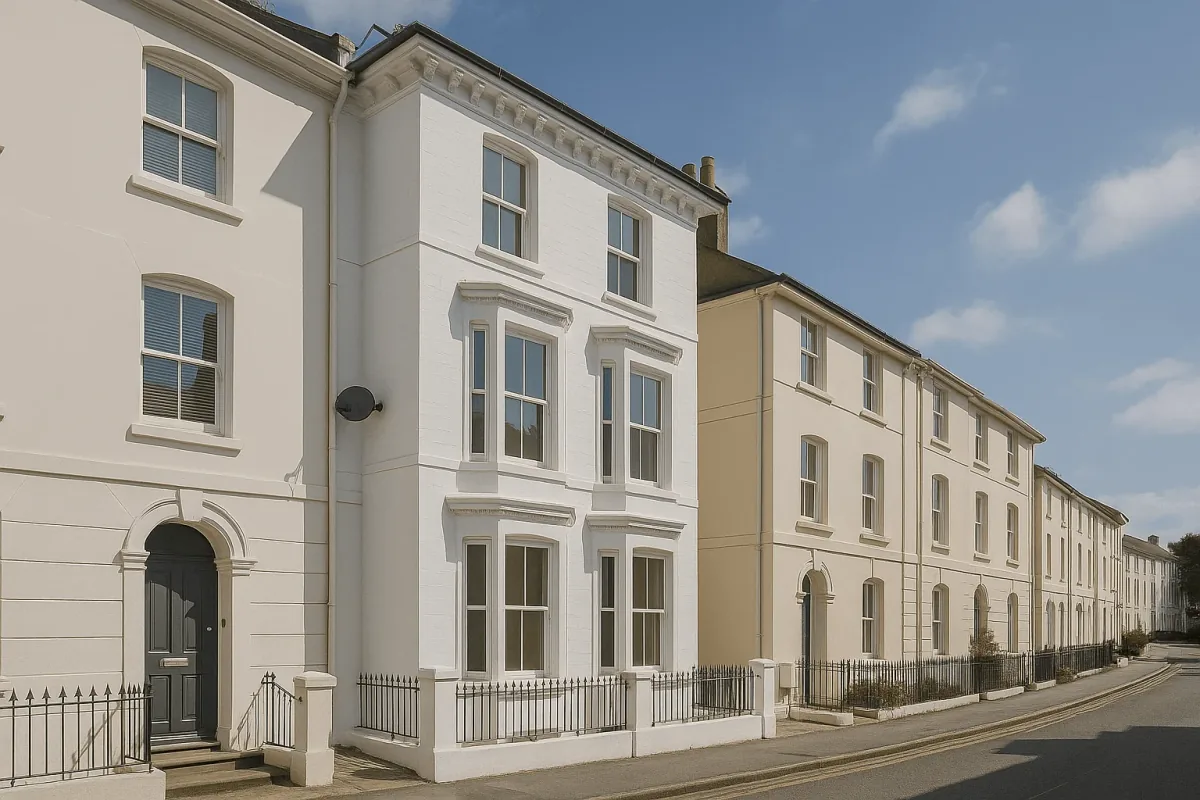
Brighton · £540K · 6 weeks
Tax Efficient Limited Company HMO Strategy
Helped a portfolio investor structure HMO purchases through limited company for maximum tax efficiency.
Limited Company HMO Mortgages Fees Guide
Typical costs involved with limited company hmo mortgages.
Arrangement Fee0.5% - 2%
- Paid to:
- Lender
- When:
- Completion
Fee charged by the lender for setting up the limited company HMO mortgage. Can typically be added to the loan amount.
Valuation Fee£400 - £1,200
- Paid to:
- Surveyor/Lender
- When:
- Application
Professional valuation of the HMO property for limited company lending. Includes assessment of commercial viability.
Legal Fees£800 - £2,500
- Paid to:
- Solicitor
- When:
- Completion
Legal costs including company documentation, property searches, and registration. More complex than personal mortgages.
Company Setup Fee£100 - £500
- Paid to:
- Accountant/Agent
- When:
- Before Application
Cost of setting up SPV company if required. Includes company registration and initial documentation.
Broker Fee0.5% - 1.5%
- Paid to:
- Broker
- When:
- Completion
Fee for arranging the limited company HMO mortgage, reflecting the additional underwriting and structuring work involved.
Annual Company Costs£200 - £800
- Paid to:
- Various
- When:
- Annually
Ongoing costs including Companies House filing, accountancy, and corporate banking fees.
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .
Limited Company HMO Mortgages FAQs
What is a limited company HMO mortgage?
A limited company HMO mortgage is a specialist buy-to-let mortgage where the borrowing entity is a registered UK limited company rather than an individual. Since tax changes introduced in 2017 (Section 24 of the Finance Act 2015), which phased out the ability for individual landlords to deduct mortgage interest in full from rental income, there has been a significant shift toward purchasing and refinancing HMOs through limited company structures — most commonly Special Purpose Vehicles (SPVs) set up specifically to hold property. The key advantage is that a limited company can still deduct 100% of mortgage interest as a business expense before calculating corporation tax, unlike individual landlords who are now restricted to a 20% basic rate tax credit. This makes the limited company route particularly attractive for higher or additional rate taxpayers. The mortgage itself works similarly to a personal HMO mortgage: the lender assesses the company's ability to service the debt based on rental income, applies a stress test, and requires a minimum deposit (typically 25-30%). The main differences are that rates are generally 0.5-1% higher than personal mortgages, the lender will require personal guarantees from the directors, and company accounts or a business plan will be needed if the company is newly formed. Most lenders require the company to have an SIC code of 68100 or 68209 (property rental activities). If you are considering whether to buy in personal name or through a limited company, always take personalised tax and legal advice first, as the decision depends on your income level, portfolio size, and longer-term strategy.
David Sampson · Updated 17 May 2026
Are rates higher for limited company HMO mortgages?
Limited company HMO rates are often similar to personal ownership at the same LTV, though the best deals depend on trading history, director guarantees, and rental stress tests. Some lenders add a small premium (typically 0.1–0.3%) for newer SPVs with no track record. The real saving is usually tax efficiency — mortgage interest remains deductible in the company, unlike personal Section 24 restrictions. Compare net cost after corporation tax and dividend tax, not just the headline rate.
Milly Turner · Updated 17 May 2026
What documents are needed for a limited company HMO mortgage?
You will need company documents (certificate of incorporation, memorandum, shareholders), latest company accounts or accountant's certificate, three to six months of business bank statements, director ID and proof of address, property details, HMO licence, tenancy schedule, and personal guarantees from directors where required. Lenders also want to see the property is held in an SPV or trading company acceptable to their panel. Having a clean company structure without unrelated activities speeds underwriting.
Sarah Johnson · Updated 17 May 2026
What are the tax benefits of a limited company HMO mortgage?
The primary tax advantage of holding an HMO through a limited company is the ability to deduct 100% of mortgage interest as a business expense against rental income before calculating corporation tax. For individual landlords, since Section 24 changes took full effect from April 2020, mortgage interest deductions have been replaced by a 20% basic rate tax credit — meaning higher and additional rate taxpayers effectively pay tax on gross rental income before interest costs, significantly reducing net returns. By contrast, a limited company holding the same property can deduct the full mortgage interest, reducing the taxable profit and paying corporation tax (currently 19-25% depending on profit level) on the remainder. As a concrete example: an HMO generating £30,000 in annual rent with £15,000 in mortgage interest would have taxable profit of £15,000 in a limited company (after deducting interest). An additional rate taxpayer owning personally would pay 45% on roughly £27,000 (after only a 20% credit on the £15,000 interest). The net tax saving can be substantial. Additional benefits include: profits retained within the company are taxed at corporation tax rates rather than income tax rates, allowing more cash to be retained for reinvestment; and Entrepreneurs Relief (now Business Asset Disposal Relief) may apply to future disposals. Offsetting factors include the higher mortgage rates for limited companies (0.5-1% premium), double taxation risk when drawing profits as dividends (corporation tax plus dividend tax), and additional accounting and compliance costs. Tax laws change and individual circumstances vary significantly — always take advice from a qualified tax adviser before deciding on your ownership structure.
David Sampson · Updated 3 May 2026
How do I set up a limited company for HMO properties?
Most investors use a special-purpose vehicle (SPV) — a Ltd company whose articles restrict activity to property letting. Register via Companies House (or use a formation agent), open a business bank account, and hold each property in the company name. You will need an accountant for corporation tax returns and payroll if you pay yourself. Before buying, confirm your chosen lender accepts new SPVs and whether they require personal guarantees from directors — most do on first property.
Milly Turner · Updated 2 October 2025
How long do I need to have been trading?
For Ltd/SPV HMO purchases, many lenders accept newly incorporated companies if directors have personal landlord or employment track record. Trading history of 1–2 years in the company helps for higher LTV but is not always mandatory. Personal affordability is often assessed via directors' income, tax returns, or portfolio performance.
Sarah Johnson · Updated 3 May 2026
Can I transfer existing HMO properties to a limited company?
Yes, via a company purchase of the property from yourself, but it triggers SDLT (including surcharges), capital gains tax, and legal costs. Many landlords use incorporation relief or s.162 incorporation only in specific circumstances — take tax advice first. Lenders treat it as a new purchase or remortgage into the company. The transfer must stack up on overall tax and fees; it is not automatically cheaper than retaining personal ownership.
David Sampson · Updated 17 May 2026
What deposit is needed for a limited company HMO mortgage?
Limited company HMO mortgages typically require a minimum deposit of 25-30% of the property value, meaning the maximum loan-to-value available is 70-75%. While this mirrors the requirement for personal HMO mortgages, there are some differences in practice. Newly incorporated companies with no trading history or no track record of holding property will generally be required to provide a 30-35% deposit, as lenders view a brand-new SPV as higher risk than an established company. Experienced property investors who have been borrowing through a limited company structure for several years, and whose company demonstrates strong rental income, may access 75% LTV (25% deposit) from a wider range of lenders. The deposit must come from legitimate business funds — either equity already in the company from previous transactions, or a director's loan injection from personal funds. Gifted deposits are generally not accepted for limited company purchases, and lenders will require a clear audit trail of where the deposit originated. As an illustration: purchasing an HMO worth £400,000 through a limited company at 75% LTV would require a £100,000 deposit and a £300,000 mortgage. At 70% LTV, the deposit rises to £120,000. It is also worth noting that Stamp Duty Land Tax (SDLT) is payable at the higher 3% surcharge rate on top of standard rates for company purchases in England, which adds a further significant upfront cost — on a £400,000 purchase this surcharge alone would be approximately £12,000. Budget for this alongside the deposit when assessing total funds required.
Milly Turner · Updated 19 April 2026
How do limited company HMO mortgage rates compare to personal?
Limited company HMO mortgage rates are typically 0.5-1.5% per annum higher than equivalent personal HMO mortgages. This premium reflects the additional risk and administrative complexity for lenders when lending to a corporate entity: the company structure adds a layer of separation between the lender and the underlying asset, personal creditworthiness assessments are more complex, and the legal processes involved in enforcement in the event of a default are more involved. As a practical illustration: if a personal HMO mortgage for an equivalent property is available at 5.5% on a five-year fix, a limited company mortgage for the same property and LTV might be available at 6.0-6.5%. On a £300,000 mortgage, that 0.5% premium adds £125 per month (£1,500 per year) in additional interest costs; a 1% premium adds £250 per month (£3,000 per year). This cost differential is a key consideration in the personal-versus-company ownership decision: for a higher-rate taxpayer, the tax savings from operating through a limited company (via full mortgage interest deductibility against corporation tax) can significantly outweigh the higher mortgage rate premium. However, for a basic rate taxpayer with a small portfolio, the rate premium may wipe out any tax advantage. The number of lenders active in the limited company HMO space has grown considerably since 2017, increasing competition and narrowing the rate gap compared to a few years ago. A specialist broker will be able to run a side-by-side comparison of personal versus limited company rates from current live products, which is the most reliable way to quantify the actual cost difference for your specific situation.
Sarah Johnson · Updated 8 March 2026
What are the eligibility criteria for limited company HMO mortgages?
Lenders typically want a UK-registered Ltd/SPV, directors with acceptable credit, demonstrable rental income on the HMO, valid licensing, and LTV up to 75% (sometimes 80% for strong cases). New SPVs are accepted by many specialists without trading history if directors have landlord experience. Personal guarantees are common. Properties must meet minimum room sizes and HMO standards; some lenders cap number of rooms or require experienced management.
David Sampson · Updated 26 April 2026
Limited Company HMO Mortgages Key Terms
- SPV (Special Purpose Vehicle)A limited company set up solely for the purpose of holding property investments, often used for tax efficiency and risk management.
- Limited Company MortgageA mortgage taken out by a limited company rather than an individual, often used for property investment to benefit from different tax treatment.
- Company StructureThe legal and organizational setup of a limited company, crucial for tax planning and mortgage applications.
- Section 24UK tax legislation that restricts mortgage interest relief for individual landlords to the basic rate of tax (20%). This significantly impacts the profitability of highly leveraged property investments and has driven many landlords to incorporate their property businesses or use limited companies for new purchases.
CeMAP Qualified
DipFA
CeMAP (Certificate in Mortgage Advice and Practice)
DipFA (Diploma in Financial Advice)
15+ years mortgage industry experience
Arranged £187M+ in HMO lending
4,000+ clients helped
Founded The HMO Mortgage Broker
HMO Mortgages
Development Finance
Portfolio Lending
Commercial Finance
HMO Finance Specialist
Property Investment Specialist
About the author
David is the founder and senior HMO mortgage specialist with over 15 years of experience in property finance. He founded the firm in 2013, which has since helped 4,000+ landlords secure HMO finance.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.