.svg)
Bad Credit HMO Mortgages | Adverse Credit Specialists (2026)
Access HMO mortgages despite adverse credit with specialist lenders. Focus on rental income potential rather than credit history with rates from 6.5% and manual underwriting.
Bad Credit HMO Mortgages at a glance
- Max LTV
- 65%
- Indicative rates from
- 6.5%
- Max term
- 25 years
- Typical timeline
- 6-8 weeks
Typically suits borrowers with
- CCJs, defaults considered
- Minimum 30-35% deposit
- Strong rental income potential
Indicative figures; the rate and terms you're offered depend on your circumstances and the property.
What are Bad Credit HMO Mortgages?
A bad credit HMO mortgage is a specialist loan for landlords with past credit problems, such as CCJs, defaults or missed payments, who want to buy or refinance an HMO. Lenders underwrite manually, focusing on the property's rental income and your current finances rather than your credit score alone, and usually ask for a 30–35% deposit.
These lenders focus primarily on the property's rental income potential and the borrower's current financial situation rather than historical credit issues.
specialist Lending for Credit Challenges
Adverse credit can include CCJs, defaults, missed payments, debt management plans, or even previous bankruptcies.
specialist lenders take a more holistic view of your application, considering not just your credit history but also the strength of your investment opportunity and your current financial position. They understand that past credit issues may have been due to circumstances beyond your control, such as business difficulties, relationship breakdowns, or temporary financial setbacks.
These lenders focus on your ability to service the mortgage going forward, rather than dwelling on past problems. Many specialist lenders will consider your rental income potential, your experience as a landlord, and the property's location and condition when assessing your application.
Bad Credit HMO Mortgage Requirements
Bad credit HMO mortgages typically require larger deposits (30-35%) and carry higher interest rates, but they provide a pathway for investors to rebuild their credit while generating rental income.
Many specialist lenders offer manual underwriting, considering individual circumstances and the strength of the proposed HMO investment. You'll typically need to provide comprehensive financial documentation including bank statements, proof of income, and evidence of your ability to service the mortgage.
Some lenders may require additional security or guarantees to offset the credit risk. This might include a larger deposit, a guarantor, or additional collateral. Interest rates may also be higher than standard HMO mortgages, reflecting the increased risk to the lender.
Successfully maintaining these mortgages can lead to refinancing opportunities with better rates as credit scores improve over time.
If you've faced credit challenges, it's wise to check your credit score before applying.
Can you get an HMO mortgage with adverse credit?
In short: yes — specialist lenders focus on rental income, deposit strength, and your current financial position rather than historic blips alone. CCJs, defaults, debt management plans, and discharged bankruptcies may all be considered case by case. Expect higher deposits (often 30–35%) and rates above standard HMO products until your credit file recovers.
How to strengthen a bad-credit application
Provide a clear narrative for past issues, evidence of repaired credit, strong HMO cash flow, and professional management where possible. A larger deposit or additional security can offset risk. Maintaining the mortgage without missed payments helps you refinance to mainstream rates later. We use manual-underwriting lenders and present your case holistically rather than relying on automated credit scores alone.
Other HMO Mortgage Types
Explore our other specialist solutions, or return to the hub for HMO mortgages.
Key Features of Bad Credit HMO Mortgages
Adverse Credit Specialists
Lenders who understand complex credit situations.
Rental Income Focus
Emphasis on property cash flow rather than credit history.
Credit Repair Guidance
Support to improve credit while building your portfolio.
Case-by-Case Review
Manual underwriting for individual circumstances.
Secured Applications
Confidential process that won't impact credit further.
Future Refinancing
Path to better rates as credit improves.
Bad Credit HMO Mortgages Eligibility Requirements
Understanding eligibility requirements helps you prepare a successful application. Our specialist lenders assess applications based on both property characteristics and borrower circumstances, with flexibility for experienced investors and first-time landlords alike. While these are general guidelines, many lenders offer flexible criteria. Our brokers work with specialist lenders who understand HMO investments and can find solutions even if you don't meet every requirement.
Property requirements
- Yes:Strong rental yield essentialLenders assess rental yield potential through local market analysis and property characteristics. Higher yields (typically 8%+) improve your chances of approval and may access better rates.
- Yes:Good location and conditionProperties in areas with good transport links, local amenities, and strong rental demand typically receive more favourable lending terms.
- Yes:Valid HMO licence
- Yes:Professional managementSome lenders require professional property management, especially for large HMOs or first-time landlords. This ensures compliance and proper tenant management.
Borrower requirements
- Yes:CCJs, defaults consideredBad credit HMO lenders specialise in cases with CCJs, defaults, or other adverse credit. They typically require higher deposits (30-35%) and may charge higher rates.
- Yes:Minimum 30-35% depositDeposit requirements vary by product type and lender. Most HMO products require 25-30% deposit, though some specialist products may require higher deposits.
- Yes:Strong rental income potentialFor bad credit cases, lenders place greater emphasis on rental income potential. Strong rental yields help offset credit concerns and improve approval chances.
- Yes:Willingness to work on credit repairLenders want to see that you're actively working to improve your credit situation. This can include paying off debts, disputing errors, or working with credit repair services.
Common eligibility questions
What if I don't have landlord experience?
Many lenders accept first-time landlords, especially if you have a strong financial position, professional property management arrangements, or relevant business experience. Our brokers can help identify lenders suitable for your situation.
What credit score do I need for bad credit hmo mortgages?
Most lenders look for good credit history, though some specialist lenders may consider cases with minor credit issues. Recent defaults or CCJs may limit your options, but we work with lenders who specialise in adverse credit cases.
Can I get a mortgage with less than 25% deposit?
While 25% deposit is standard, some lenders may offer up to 80% LTV (20% deposit) for experienced landlords with strong portfolios. Our brokers can assess your specific situation and identify lenders offering higher LTV options.
What if my property doesn't have an HMO licence yet?
Properties requiring an HMO licence must have valid licensing before mortgage completion. If you're purchasing a property that needs licensing, we can help coordinate the application process and work with lenders who understand HMO licensing requirements.
Bad Credit HMO Mortgages Process
Our mortgage process, step by step.
- 1
Credit Assessment Consultation
45 minutes - 2
Enhanced Application Process
2-3 days - 3
Property Valuation & Assessment
1-2 weeks - 4
Specialist Underwriting
3-5 weeks - 5
Legal Process
2-4 weeks - 6
Completion
Same day
Bad Credit HMO Mortgages Calculators
Current Bad Credit HMO Mortgages Rates
Live rates from our specialist lenders for bad credit hmo mortgages. Monthly payments shown are calculated using a representative example of £250,000 loan amount.
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .
Bad Credit HMO Mortgages Success Stories
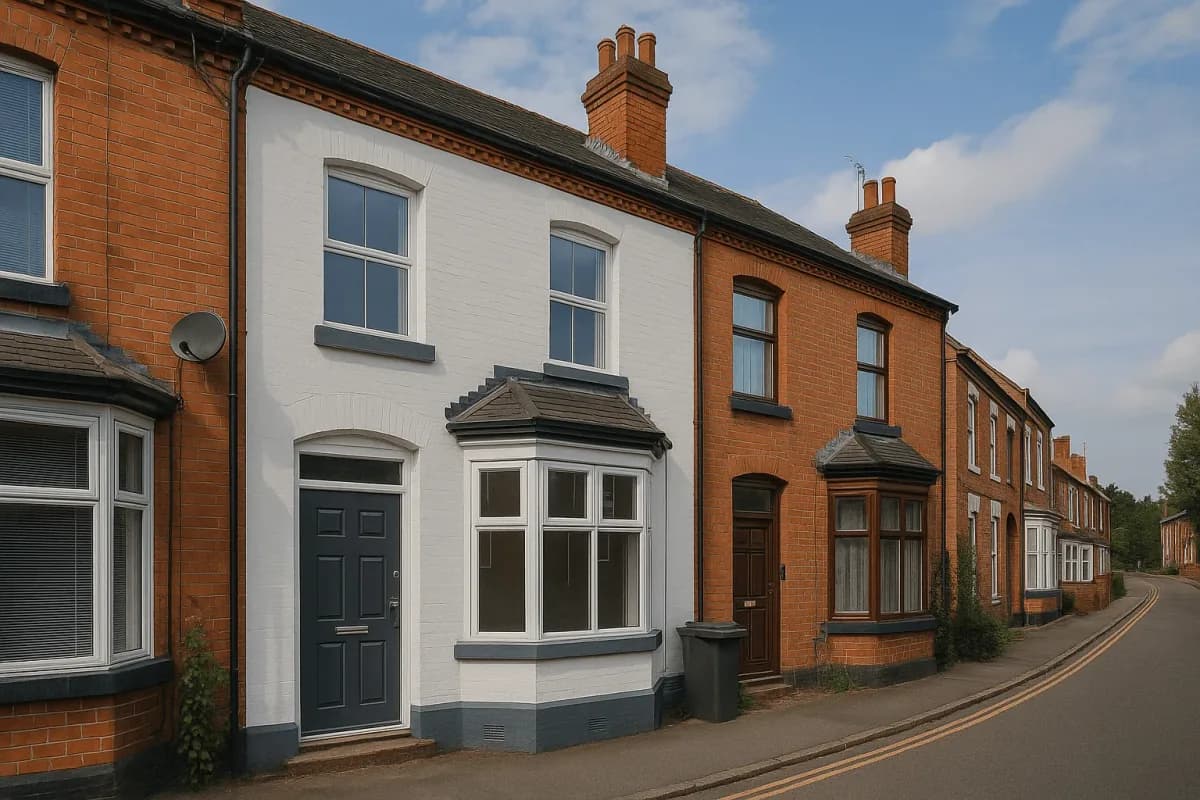
Birmingham · £224K · 7 weeks
HMO Success After Credit Recovery
Helped an investor rebuild their portfolio with an HMO purchase after recovering from past credit issues.
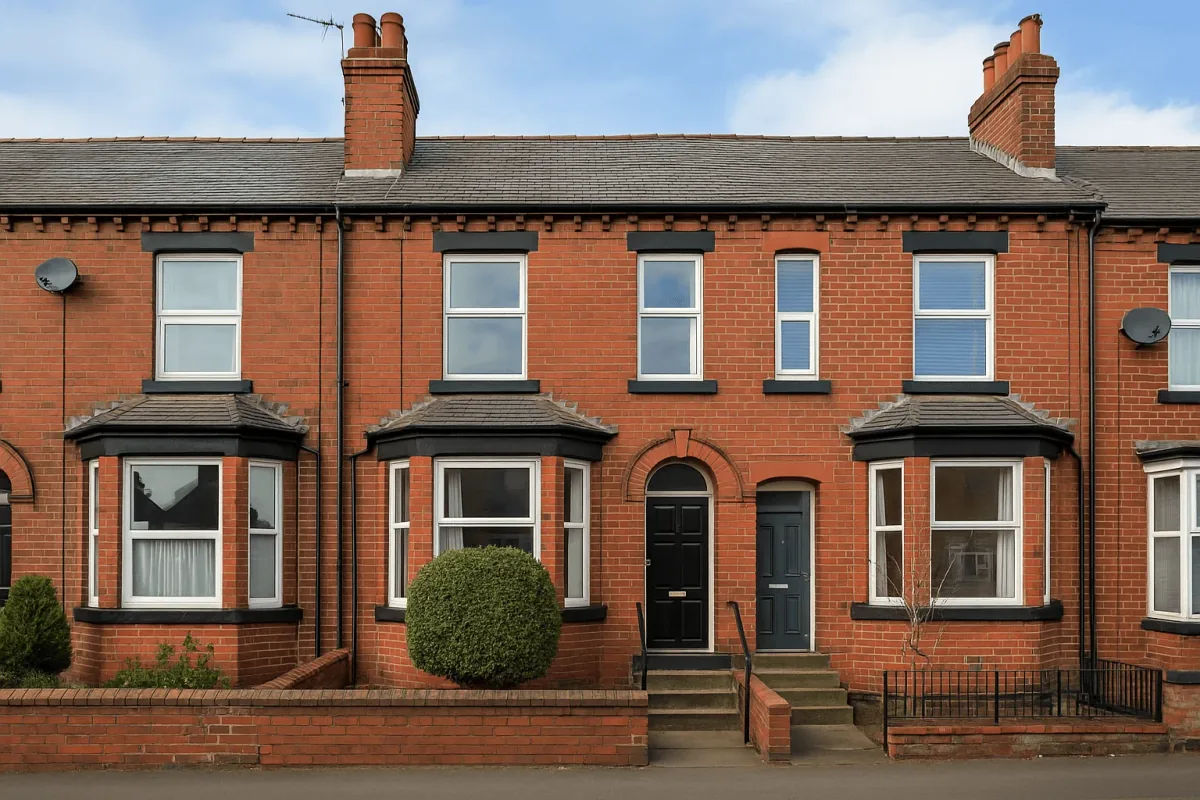
Leeds · £200K · 6 weeks
Post-IVA HMO Investment Success
Helped an investor secure HMO mortgage after completing an Individual Voluntary Arrangement (IVA).
Bad Credit HMO Mortgages Fees Guide
Typical costs involved with bad credit hmo mortgages.
Arrangement Fee2% - 4%
- Paid to:
- specialistLender
- When:
- Completion
Fee charged by specialist bad credit lenders for HMO mortgages. Higher fees reflect additional risk assessment and manual underwriting.
Valuation Fee£400 - £1,200
- Paid to:
- Surveyor/Lender
- When:
- Application
Professional valuation with emphasis on rental income potential to offset credit concerns. May require specialistHMO valuers.
Legal Fees£800 - £2,500
- Paid to:
- Solicitor
- When:
- Completion
Legal costs for bad credit HMO mortgage including additional compliance checks and documentation requirements.
Credit Assessment Fee£200 - £600
- Paid to:
- specialistLender
- When:
- Application
Fee for detailed manual credit assessment and case review by specialist bad credit underwriters.
Broker Fee1% - 2%
- Paid to:
- specialistBroker
- When:
- Completion
Fee for arranging bad credit HMO mortgage. Specialist knowledge of adverse credit lending commands premium fees.
Higher Lending Charge£300 - £800
- Paid to:
- Lender
- When:
- Completion
Additional charge to cover increased risk associated with adverse credit lending. Applied to most bad credit mortgages.
Bad Credit HMO Mortgages FAQs
Can I get an HMO mortgage with bad credit?
Yes, it is possible to get an HMO mortgage with bad credit, but you will need to work with specialist lenders rather than mainstream banks, and you should expect higher rates, a larger deposit requirement, and more stringent criteria overall. The key factors lenders will assess are the type of adverse credit, its severity, and how recently it occurred. Missed payments on bills or credit cards, if more than two to three years old, are often treated more leniently. County Court Judgements (CCJs), defaults, or Individual Voluntary Arrangements (IVAs) are more serious and will significantly narrow the range of lenders willing to consider your application. A recent bankruptcy or repossession within the last three years is likely to make any HMO mortgage unattainable until more time has passed. As a general guide: for adverse credit that is more than three years old and has been resolved, a 30% deposit and rates of 6.5-8% are typical. For more recent or more severe adverse credit, a 35-40% deposit may be required and rates can exceed 9%. An experienced HMO mortgage broker is particularly important in this situation — they will know which specialist lenders are active in the adverse credit space, how to frame your application to present your case in the strongest possible light, and whether you would be better served by waiting, rebuilding your credit score, and applying in 12-24 months when you may access materially better terms. Never make multiple applications directly with lenders, as each credit search leaves a footprint that can further damage your credit score.
David Sampson · Updated 10 May 2026
What types of bad credit are considered?
Specialist lenders consider CCJs, defaults, missed payments, debt management plans, IVAs, and discharged bankruptcies — severity and recency matter. A satisfied CCJ over three years old is viewed differently from recent missed mortgage payments. Many focus on current affordability and rental income rather than historic blips alone.
Milly Turner · Updated 10 May 2026
How much deposit do I need with bad credit?
Adverse-credit HMO deposits are often 30–35% (65–70% LTV), sometimes higher for recent serious issues. Improving credit, waiting for issues to age, or using a larger rental surplus can improve terms. A larger deposit reduces lender risk and widens the available lender panel.
Sarah Johnson · Updated 3 May 2026
What are the typical interest rates for bad credit HMO mortgages?
Rates commonly fall between 6% and 9% depending on credit severity, LTV, and experience — roughly 1–2% above clean-credit HMO products. Two-year fixes are standard; longer fixes may be available at a premium. Always compare total cost over the fix period, not headline rate alone.
David Sampson · Updated 5 April 2026
How long do I need to wait after bad credit before applying?
No fixed rule — satisfied CCJs over three years old are often acceptable; recent missed mortgage payments are harder. Some lenders accept discharged bankruptcies after 3–6 years. The longer issues are satisfied and explained, the better the rate and LTV.
Milly Turner · Updated 26 April 2026
How do I improve my credit score for an HMO mortgage?
Register on the electoral roll, clear defaults where possible, keep credit utilisation low, avoid new payday credit, and ensure all accounts are paid on time for 12+ months. Check all three bureau files for errors. Specialist brokers match you to lenders whose scoring tolerates your profile.
Sarah Johnson · Updated 26 April 2026
What documents do I need for a bad credit HMO mortgage?
Standard HMO pack plus a written explanation of adverse credit, proof issues are satisfied, bank statements showing stable income, and strong rental evidence. Some lenders want higher deposits evidenced for six months. Bankruptcy or IVA discharge certificates if applicable.
David Sampson · Updated 17 May 2026
How long does a bad credit HMO mortgage application take?
Often 6–8 weeks — manual underwriting takes longer than automated decisions. Complete files with credit explanation letters avoid back-and-forth delays. Instruct valuation early once documents are submitted to keep the file moving.
Milly Turner · Updated 5 April 2026
What are the eligibility criteria for bad credit HMO mortgages?
Acceptable rental income, valid HMO licence where required, larger deposit (often 30%+), and demonstrated affordability. Severity and recency of credit issues determine lender choice. Experience as a landlord can offset weaker credit.
Sarah Johnson · Updated 12 April 2026
Can I get a bad credit HMO mortgage with a guarantor?
A small number of lenders accept guarantors or joint applicants with stronger credit; most adverse-credit HMO products rely on rental income and deposit rather than guarantors. Family assistance via gifted deposit is more common than formal guarantees.
David Sampson · Updated 26 April 2026
Bad Credit HMO Mortgages Key Terms
- Bad CreditA poor credit history or credit score resulting from missed payments, defaults, County Court Judgments (CCJs), debt management plans, or other adverse credit events. For HMO mortgage applications, lenders assess the severity, recency, and reasons behind credit issues when considering applications.
- Bad Credit MortgageA mortgage product designed for borrowers with a poor credit history, often with higher interest rates and stricter terms.
- Credit RepairThe process of improving a poor credit score to increase chances of mortgage approval and better rates.
- Bad Credit DepositThe higher deposit required for borrowers with adverse credit, typically 30% or more.
CeMAP Qualified
DipFA
CeMAP (Certificate in Mortgage Advice and Practice)
DipFA (Diploma in Financial Advice)
15+ years mortgage industry experience
Arranged £187M+ in HMO lending
4,000+ clients helped
Founded The HMO Mortgage Broker
HMO Mortgages
Development Finance
Portfolio Lending
Commercial Finance
HMO Finance Specialist
Property Investment Specialist
About the author
David is the founder and senior HMO mortgage specialist with over 15 years of experience in property finance. He founded the firm in 2013, which has since helped 4,000+ landlords secure HMO finance.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.