.svg)
HMO Portfolio Mortgages | Rates from 4.3% | 3+ Properties (2026)
Unlock portfolio-level benefits with specialistHMO mortgages. Get better rates as your portfolio grows, cross-collateralize properties, and access rates from 4.3% with dedicated support.
HMO Portfolio Mortgages at a glance
- Max LTV
- 75%
- Indicative rates from
- 4.3%
- Max term
- 30 years
- Typical timeline
- 6-8 weeks
Typically suits borrowers with
- Experienced portfolio landlord
- Strong track record
- Professional management
Indicative figures; the rate and terms you're offered depend on your circumstances and the property.
What are HMO Portfolio Mortgages?
A portfolio HMO mortgage is finance for experienced landlords who own several HMOs and want them funded under one facility rather than one mortgage per property. Lenders assess the portfolio as a whole and typically look for at least three HMOs with strong rental performance, a proven track record and professional management.
These mortgages offer more adaptable terms, potentially better rates, and simplified administration compared to individual property mortgages.
Benefits of Portfolio HMO Financing
Portfolio mortgages provide significant advantages for experienced HMO investors. Consolidating multiple properties under one facility simplifies administration, reduces paperwork, and can lead to better interest rates due to the larger loan size.
They often include portfolio management tools and reporting requirements to help investors track performance across their entire HMO portfolio. This centralised approach makes it easier to monitor cash flow, identify underperforming properties, and make strategic decisions about your portfolio.
Additionally, portfolio financing can provide more flexibility in terms of property mix, allowing you to include properties at different stages of development or with varying rental yields.
Portfolio HMO Mortgage Criteria
Lenders typically require a minimum portfolio size (usually 3+ properties) and proven track record of successful HMO management.
Portfolio mortgages can provide cross-collateralisation benefits, where stronger properties can support weaker ones in the portfolio. This means lenders may be more adaptable with individual property valuations if your overall portfolio is strong.
To qualify, you'll typically need to demonstrate a successful history of HMO management, provide evidence of consistent rental income across your portfolio, and show that you have the experience and systems in place to manage multiple properties effectively.
Who benefits from portfolio HMO finance?
In short: landlords with several HMOs who want one facility, one relationship, and potentially better pricing through scale. Portfolio mortgages suit investors refinancing multiple properties together, adding acquisitions under an existing umbrella, or simplifying administration across SPVs. They are less suitable for a single first purchase unless you already hold other mortgaged properties elsewhere.
How portfolio underwriting works
Lenders assess aggregate rental income, weighted LTV across the pool, and your experience managing multiple HMOs. You may need consolidated accounts, property schedules, and evidence of void rates and maintenance reserves. Benefits can include streamlined renewals, cross-collateral flexibility, and relationship pricing after two or more properties. We structure applications to highlight strong performers in the portfolio while explaining any weaker assets transparently.
Before consolidating, compare whether individual product rates on your strongest assets would beat a blended portfolio price — we model both scenarios so you can decide with numbers, not assumptions. Most portfolio facilities require at least three mortgaged properties, though some lenders accept two strong HMOs with experienced landlords.
Other HMO Mortgage Types
Explore our other specialist solutions, or return to the hub for HMO mortgages.
Key Features of HMO Portfolio Mortgages
Portfolio Discounts
Better rates and terms for larger HMO portfolios.
Cross-Collateral
Use existing properties as additional security.
Bulk Applications
Process multiple HMO applications simultaneously.
Portfolio Management
Dedicated account management for your HMO portfolio.
adaptable Refinancing
Options to refinance and release equity across the portfolio.
Growth Support
Financing solutions to accelerate portfolio expansion.
HMO Portfolio Mortgages Eligibility Requirements
Understanding eligibility requirements helps you prepare a successful application. Our specialist lenders assess applications based on both property characteristics and borrower circumstances, with flexibility for experienced investors and first-time landlords alike. While these are general guidelines, many lenders offer flexible criteria. Our brokers work with specialist lenders who understand HMO investments and can find solutions even if you don't meet every requirement.
Property requirements
- Yes:Minimum 3 HMO propertiesPortfolio mortgages typically require a minimum of 3 HMO properties. Some lenders may accept 2 properties if you have strong experience and portfolio performance.
- Yes:Strong rental performancePortfolio lenders assess the overall performance of your properties, looking for consistent rental income, low void periods, and good tenant retention.
- Yes:Geographic spread acceptableSome portfolio lenders prefer properties spread across different areas to reduce risk. However, concentrated portfolios in strong markets may also be acceptable.
- Yes:Well-maintained portfolioLenders expect properties to be well-maintained and compliant with all regulations. Evidence of regular maintenance and compliance helps strengthen applications.
Borrower requirements
- Yes:Experienced portfolio landlordPortfolio mortgages are designed for landlords with multiple properties. Lenders typically require experience managing 3+ properties and a proven track record.
- Yes:Strong track recordLenders assess your track record through rental income history, property management experience, and payment history on existing mortgages. A strong track record improves approval chances.
- Yes:Professional managementSome lenders require or prefer professional property management, especially for complex properties or landlords with limited experience. This ensures compliance and effective tenant management.
- Yes:Substantial asset basePortfolio lenders may require evidence of substantial assets to support your portfolio. This provides security and demonstrates your financial stability.
Common eligibility questions
What if I don't have landlord experience?
Many lenders accept first-time landlords, especially if you have a strong financial position, professional property management arrangements, or relevant business experience. Our brokers can help identify lenders suitable for your situation.
What credit score do I need for hmo portfolio mortgages?
Most lenders look for good credit history, though some specialist lenders may consider cases with minor credit issues. Recent defaults or CCJs may limit your options, but we work with lenders who specialise in adverse credit cases.
Can I get a mortgage with less than 25% deposit?
While 25% deposit is standard, some lenders may offer up to 80% LTV (20% deposit) for experienced landlords with strong portfolios. Our brokers can assess your specific situation and identify lenders offering higher LTV options.
What if my property doesn't have an HMO licence yet?
Properties requiring an HMO licence must have valid licensing before mortgage completion. If you're purchasing a property that needs licensing, we can help coordinate the application process and work with lenders who understand HMO licensing requirements.
HMO Portfolio Mortgages Process
Our mortgage process, step by step.
- 1
Portfolio HMO Consultation
45 minutes - 2
Portfolio Application Process
2-3 days - 3
Portfolio Property Valuation
1-2 weeks - 4
Portfolio Underwriting
3-4 weeks - 5
Portfolio Legal Process
2-4 weeks - 6
Portfolio Completion
Same day
HMO Portfolio Mortgages Calculators
Current HMO Portfolio Mortgages Rates
Live rates from our specialist lenders for hmo portfolio mortgages. Monthly payments shown are calculated using a representative example of £250,000 loan amount.
Important: Rates shown are indicative and subject to status. Your home may be repossessed if you do not keep up repayments on your mortgage. Terms and conditions apply. For current rates and full details, please .
HMO Portfolio Mortgages Success Stories
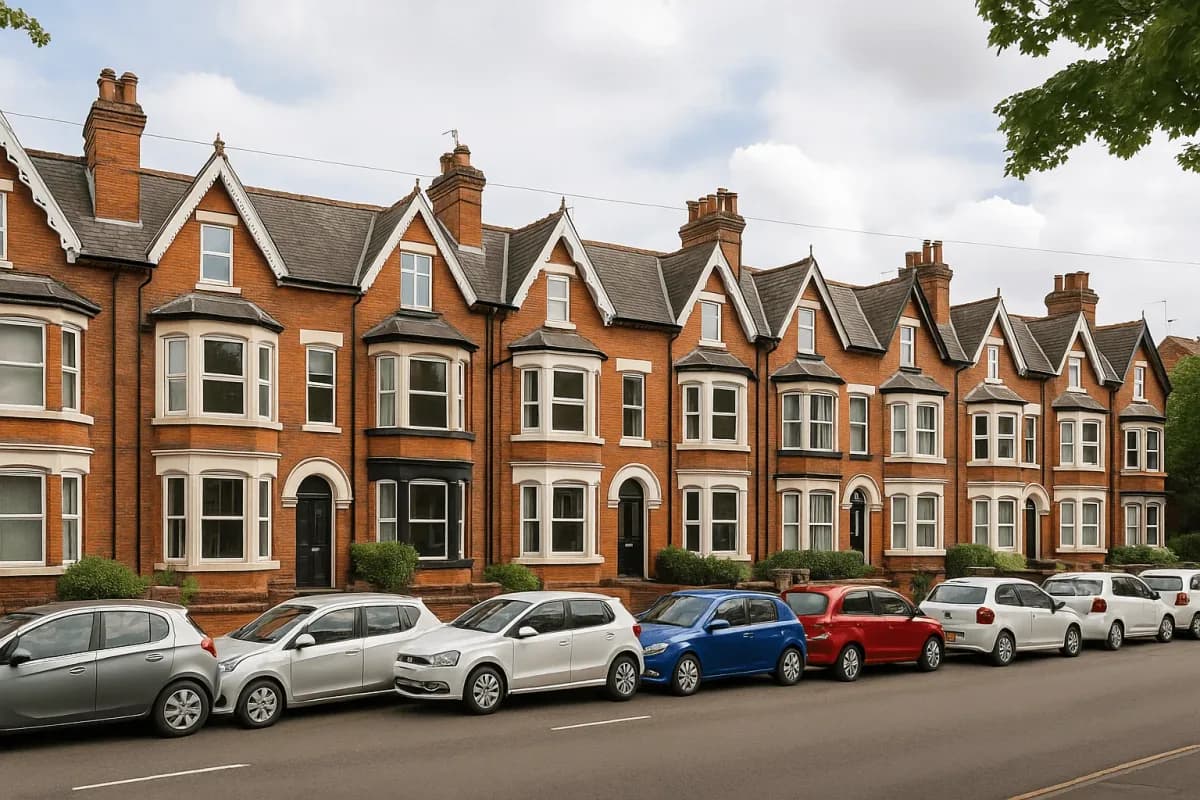
Birmingham (various) · £2.1M · 8 weeks
Portfolio Expansion: 10-Property HMO Portfolio
Secured portfolio financing for an experienced landlord expanding their HMO portfolio across Birmingham.
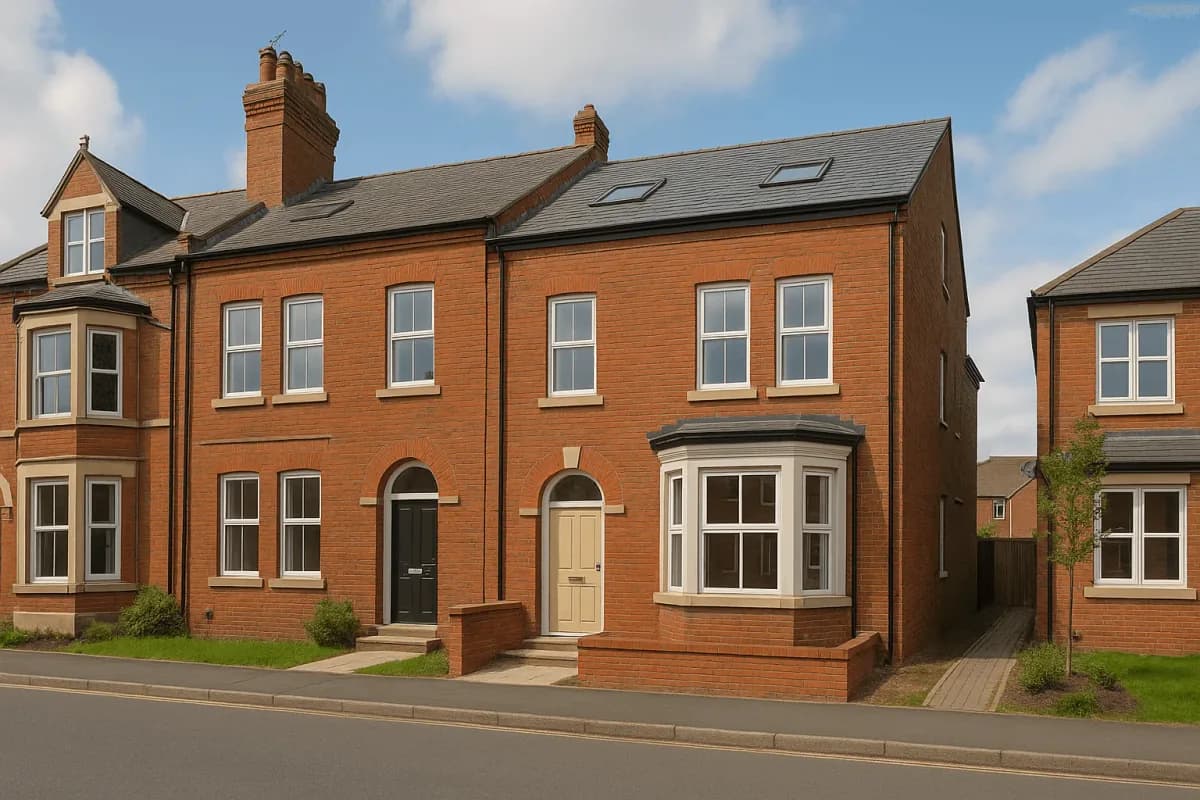
Yorkshire · £1.1M · 8 weeks
Yorkshire HMO Portfolio Expansion
Arranged portfolio mortgage facility for expanding across multiple Yorkshire towns with specialist HMO lender.
HMO Portfolio Mortgages Fees Guide
Typical costs involved with hmo portfolio mortgages.
Arrangement Fee0% - 1.5%
- Paid to:
- Lender
- When:
- Completion
Fee charged by the lender for setting up the portfolio HMO mortgage. Often discounted for larger portfolios.
Valuation Fee£300 - £800
- Paid to:
- Surveyor/Lender
- When:
- Application
Professional valuation of each HMO property in the portfolio. Bulk discounts may apply for multiple properties.
Legal Fees£500 - £1,500
- Paid to:
- Solicitor
- When:
- Completion
Legal costs per property in the portfolio. Economies of scale often reduce per-property costs.
Portfolio Management Fee£200 - £500
- Paid to:
- Lender
- When:
- Annually
Annual fee for managing the portfolio mortgage account and cross-collateral arrangements.
Broker Fee0.5% - 1%
- Paid to:
- Broker
- When:
- Completion
Fee for arranging the portfolio HMO mortgage. Often negotiated as percentage of total portfolio value.
Telegraphic Transfer£25 - £50
- Paid to:
- Lender
- When:
- Completion
Fee for transferring funds electronically for each property completion in the portfolio.
HMO Portfolio Mortgages FAQs
What is a portfolio HMO mortgage?
A portfolio HMO mortgage is designed for landlords with multiple HMO properties, offering more flexible terms. These mortgages typically have lower rates and higher borrowing limits for experienced investors.
David Sampson · Updated 22 March 2026
How many properties do I need for a portfolio HMO mortgage?
There is no single rule — portfolio products start from around 4+ mortgaged properties with some lenders, while others specialise at 10+ units. What matters is total portfolio rental income, aggregate LTV, and your experience. Some lenders offer portfolio underwriting (global affordability) rather than assessing each property in isolation, which can release more borrowing capacity across the book.
Milly Turner · Updated 17 May 2026
What are the benefits of portfolio HMO mortgages?
Portfolio lending can simplify applications (one underwriting review for multiple assets), cross-collateralise rental income, and unlock better rates as your book grows. Fixed-rate rebalancing across the portfolio, interest-only options, and Ltd company portfolio products are available from specialist lenders. It also reduces repeated arrangement fees compared with remortgaging each property separately through different lenders.
Sarah Johnson · Updated 26 April 2026
How do portfolio HMO mortgage rates compare to standard HMO mortgages?
Rates are often comparable or slightly better at lower aggregate LTV (below 60% portfolio LTV). At higher leverage, portfolio products may price 0.25–0.5% above single-asset deals because of concentration risk. The main gain is underwriting flexibility — strong aggregate cash flow can support purchases that a single-property stress test would fail.
David Sampson · Updated 3 May 2026
How do I manage multiple HMO properties?
Management includes centralized administration, standardized processes, bulk purchasing, and often professional property management services. This approach helps reduce costs and improve efficiency across your portfolio.
Milly Turner · Updated 17 May 2026
What deposit do I need for a portfolio HMO mortgage?
On a new portfolio acquisition, expect 25–30% deposit per asset (70–75% LTV) unless aggregate portfolio LTV pulls you lower. Adding properties to an existing portfolio may allow top-slicing of rental surplus to reduce deposit needs on the next purchase. Lenders review the whole schedule of properties, mortgages, and rents — not just the new asset.
Sarah Johnson · Updated 26 April 2026
What are the eligibility criteria for portfolio HMO mortgages?
Typically 3+ properties (sometimes fewer if high value), demonstrable landlord track record, acceptable credit, properties licensed where required, and rental coverage across the portfolio. Lenders want an assets-and-liabilities schedule, mortgage conduct history, and often company accounts if held in Ltd. Maximum portfolio LTV caps (e.g. 65–75% overall) apply.
David Sampson · Updated 19 April 2026
How do I apply for a portfolio HMO mortgage?
Apply through specialist lenders with portfolio details, property valuations, rental income evidence, and comprehensive business plan showing portfolio strategy. Most lenders require minimum 3-5 properties and 2+ years experience.
Milly Turner · Updated 17 May 2026
What documents do I need for a portfolio HMO mortgage?
You'll need proof of income, bank statements, portfolio details, property valuations, rental income evidence, HMO licences, and comprehensive business plan. Some lenders may also require personal guarantees and property insurance details.
Sarah Johnson · Updated 3 May 2026
How long does a portfolio HMO mortgage application take?
A single new asset within an existing portfolio relationship may complete in 4–6 weeks. First-time portfolio onboarding with multiple properties can take 8–12 weeks while the lender maps your full schedule. Having every property's rent schedule, licence, and mortgage statement ready in one pack reduces delays significantly.
David Sampson · Updated 17 May 2026
HMO Portfolio Mortgages Key Terms
- Portfolio MortgageA single mortgage that covers multiple properties, simplifying management and potentially offering better rates for experienced landlords.
- Portfolio StrategyA planned approach to building and managing a portfolio of HMO properties, considering factors like diversification, financing, and growth.
- Portfolio ManagementThe ongoing process of managing multiple properties, including tenant relations, maintenance, and financial oversight.
- Portfolio LandlordAn individual or entity owning four or more mortgaged buy-to-let properties. Portfolio landlords face stricter lending criteria under Prudential Regulation Authority (PRA) rules, including more detailed income verification, portfolio stress testing, and often higher deposit requirements.
CeMAP Qualified
CeMAP (Certificate in Mortgage Advice and Practice)
6+ years mortgage industry experience
Arranged £50M+ in HMO lending
1,200+ clients helped
Portfolio Expansion Specialist
HMO Mortgages
Portfolio Finance
First-Time Landlords
Buy-to-Let
HMO Finance Specialist
Portfolio Management Specialist
New Landlord Advisor
About the author
Milly is a senior HMO mortgage adviser with extensive experience in property finance and portfolio management.
Free initial review
Speak to an HMO specialist
30+ specialist lenders compared. Open 8am to 8pm, Monday to Saturday.